
Donald Trump proposing 50 year mortgages sparks MAGA backlash

By: Kate Plummer (Newsweek)

Debt slavery is Trump's solution for affordability? This autocratic decree is most certainly TEA Party and definitely not MAGA.
 S E E D E D C O N T E N T
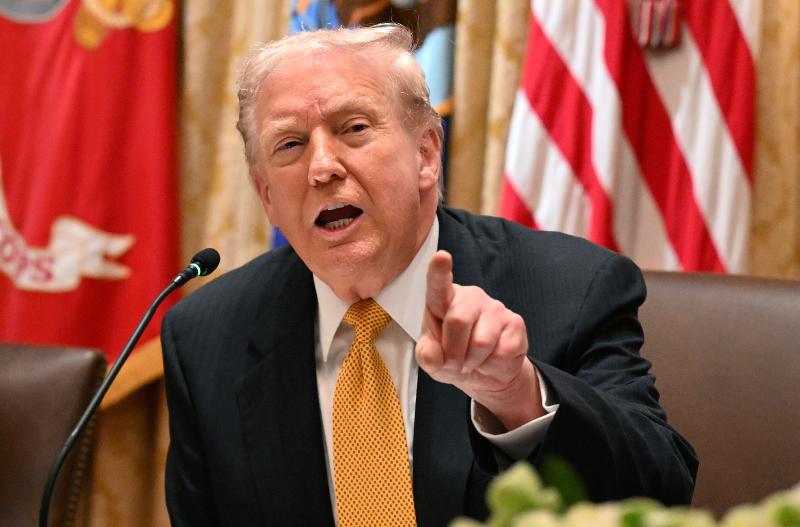
U.S. President Donald Trump's proposal to introduce 50-year mortgage terms for homebuyers has sparked a backlash from online commentators.
Federal Housing Finance Agency (FHFA) Director Bill Pulte said on Saturday that the Trump administration is working on a plan to introduce the measure.
Writing on X, people criticized the idea, which they said could increase debt levels.
A U.S. Federal Housing spokesman told Newsweek: "We continue to evaluate all options to address housing affordability, including studying how to make mortgages assumable or portable."
Why It Matters
Homeownership has emerged as a key issues in the U.S., with many people struggling to get on the housing ladder. The average age of first-time homebuyers had reached an all-time high of 40, according to a recent report by the National Association of Realtors and the U.S. housing market has slowed this year due to sky-high home prices, elevated borrowing costs and other factors.
What To Know
Pulte's X post came after Trump posted an image on his social media platform Truth Social in which he placed an image of himself next to one of former President Franklin D. Roosevelt, who established the 30-year mortgage standard. He wrote "30-year mortgage" above Roosevelt's image and "50-year mortgage" above his.
In a separate post, Pulte wrote: "Trump proposes 50-year mortgage to help affordability."
A longer fixed-rate mortgage would lower monthly payments, but would create a higher total cost because of interest.
Writing on X, some figures raised issues with the proposal.
Georgia Republican Representative Marjorie Taylor Greene wrote, in part: "I don't like 50-year mortgages as the solution to the housing affordability crisis. It will ultimately reward the banks, mortgage lenders and homebuilders while people pay far more in interest over time and die before they ever pay off their home. In debt forever, in debt for life!"
Maggie Anders, who works for the conservative libertarian think tank the Foundation for Economic Education said: "Young Americans don't want to be debt slaves for the rest of their lives. We want cheaper houses, which can only be accomplished by increasing the supply through deregulation."
Graham Stephan, a real estate investor and commentator with over 199,000 followers wrote: "A 50-Year mortgage would allow you to buy approximately 10 percent more house (or save about 10 percent) at the expense of nearly DOUBLING your payment schedule. There's no way that ends well.
"A 50-year mortgage isn't worth it and won't add much benefit since your mortgage interest is front-loaded. Homeowners will have very little, if any, equity by the time they sell (homeowners keep their home an average of 11.8 years). It sounds good on paper, but financially, it makes very little sense."
Lukas Schubert, a Montana state Republican wrote: "The best way to help young homebuyers is to deport all the 30 million illegals from this country, that will free up a lot of housing!"
Matt Walsh, a conservative commentator, wrote: "This just means your house will be owned by the bank until you die, and after. We don't need 50-year mortgages. Get the illegal immigrants out of our country. Give America back to Americans."
However, others said it was a good idea. John Pompliano, an investor with over 72,000 followers wrote: "The 30-year mortgage is one of the best financial products available to Americans. 50 years is even better."
Crypto Wendy, a cryptocurrency analyst with over 458,000 followers wrote: "I don't think a 50-year mortgage is bad. It gives everyone more flexibility financially You can pay a mortgage off early. Not sure how else to lower home costs in 2025."
What People Are Saying
Federal Housing Finance Agency Director BillPulte wrote on X Saturday: "Thanks to President Trump, we are indeed working on The 50-year Mortgage—a complete game changer."
HousingWire lead analyst Logan Mohtashami wrote: "I understand that we have housing affordability challenges in America, but subsidizing more demand from 30- to 50-year mortgages is not the policy we want to take now. Housing has to balance itself out through slowing home-price growth and wages increasing—as it has for many decades. To add another subsidization to the market just prevents that healing process from occurring, which also prevents less equity build out as well. So I am not a fan of any increasing in the amortization, the 30-year fixed is perfectly fine as is."
What Happens Next
Pulte said the administration was "working on" the plan, but further details about what that will entail and when it will be implemented remain to be seen.
Update 11/9/25 7:30 a.m. ET: This story has been updated with additional information.
Update 11/10/25 4:55 a.m. ET: This story has been updated with comment from the FHFA.
Be a good human. Grossly derogatory comments, blatantly inflammatory comments, excessive trolling, mean-spirited taunting and insults, scamming, spamming, and off topic comments may be removed in compliance with the site's Terms of Service and the Code of Conduct. The moderators have the final word.

A 50 year mortgage means very few could ever own a home. Only the rich can own real estate in the United States. Trump has given up on the American Dream.
The difficulty for young families is getting started with the first house, and a 50 year note doesn't make that significantly easier than a 30 year note.
Well let's see what the math actually says.
A house payment (PI only) on a $400k note at 6% goes as follows:
I'm not sure a sub $300 delta is the difference between home ownership or not.
That said, the idea that homeowners won't have equity when they sell the home is stupid and Graham Stephan of all people should know better. The equity you get from the sale overwhelmingly comes from the appreciation of the home, not the amount of loan you've paid off. That's why home ownership is a foundation of American wealth. Your dwelling is an appreciating asset.
Someone buying a $400k house and making monthly payments of $3375 for 15 years would pay $607,500 for the house. Someone making monthly payments of $2106 for 50 years would pay $1,263,600 for the house.
Someone selling that $400k house after making payments for 10 years would have several times more equity with a 15 year mortgage than a 50 year mortgage. That's because interest on the mortgage is front loaded.
Over the last 10 years that $400k home has appreciated to $774,000 in Texas, $790,000 in California, and $893,000 in Florida.
At the end of 10 years, you would still owe $175k on the 15 year note vs $337k on the 30 year note.
So the $162k difference in what you owe is dwarfed by the roughly $400k appreciation of the home.
Meanwhile, if you took the $1000 payment difference and invested in the S&P 500 it would now be worth $280k.
In summary, on the 15 year note, your total wealth from the overall setup (in Texas) is $774,000 home value - $175,00 loan = $599,000 net. On the 30 year loan, you have $774k home value - $337k + $280k investment account = $717,000 net.
That difference gets much the longer the arrangement goes on.
Your overall wealth is almost always better served with a 30 year note and investing the difference, IDGAF what Dave Ramsey says.
$162k is not chump change. That's 20% of the appreciated value (in Texas).
What happened to the 50 year note?
Nope. Shorter term notes and doubling the equity payment always provides the better return. That reduces the overall amount of interest paid, shortens the length of the mortgage, and allows the owner to keep more of the equity.
Sure, but still, the overwhelming majority of home equity lies in appreciated value rather than reduced debt.
I thought we decided it wasn't worth considering. I suspect for different reasons, but I can't see how it would be very popular even if it were available.
I'm sure you think so, but I also don't believe you're invested in the stock market.
Taking a 15 year mortgage is sort of like trying to squeeze more speed out of a propeller aircraft instead just using the jet.
So let’s not find a way to make housing cheaper. Instead, let’s just have people be chained to debt for their whole fucking lives.
Dumb on a lot of levels and will have zero effect on home price. If anything, it will cause prices to rise just like every other injection of money does. Giving people money causes prices to go up. Why that is such a hard concept for so many to grasp is frightening. They seem to think we live in a video game world where infinite goods are just always available to everyone.
However, the real danger to our economy is Fannie Mae's decision to eliminate minimum credit scores for loans. The 2008 crash was so fun they want to do it over again.