
Senate passes deregulation bill scaling back Dodd-Frank

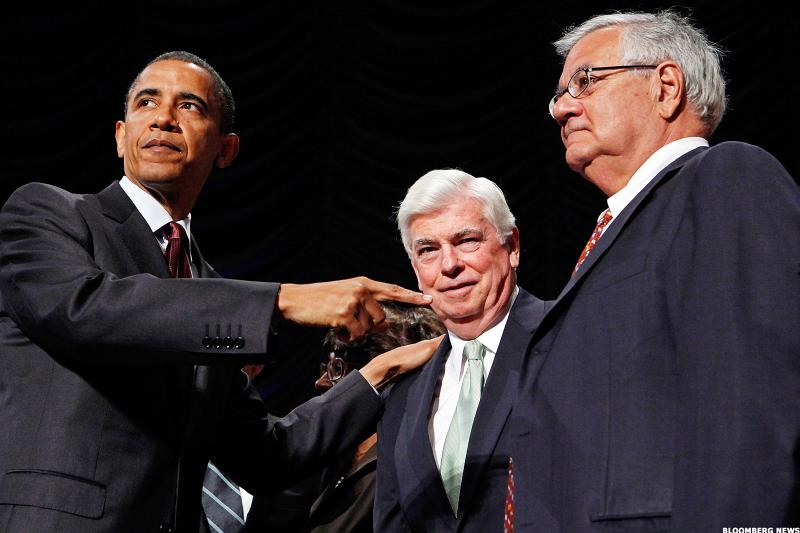

The Senate on Wednesday passed a milestone bank deregulation bill that would mark the biggest rollback of financial rules since the 2008 market meltdown.
On a day when Wall Street was observing the 10th anniversary of the Bear Stearns investment bank bailout — a pivotal moment in the global financial crisis — the Senate agreed in a 67-31 bipartisan vote to overhaul a wide range of regulations imposed on small and large lenders in the years since.
"This bill shows that we can work together and do big things that make a difference in the lives of people across this country," Senate Banking Chairman Mike Crapo (R-Idaho) said.
Yet as the dust settled after a fiery two-week debate, the bill’s backers faced the possibility that getting the legislation to President Donald Trump’s desk would be delayed — or even derailed — as House Republicans vowed to put their stamp on it.
“My job is to represent the House, and we’ve got a lot of good bills that we want to talk to the Senate about,” House Financial Services Chairman Jeb Hensarling (R-Texas) said in an interview. “I’m surprised that anybody thought we’d merely rubber-stamp their product.”
Still, the bill, which was years in the making, was a rare bipartisan accomplishment at a time when Congress is gridlocked on almost all major issues.
Sixteen moderate Senate Democrats helped Republicans pass the bill. It was an unusual moment of political unity that sparked a public feud in which the Democratic Party's progressive wing went to war with its more business-friendly centrists.
Liberal icon and potential 2020 presidential candidate Sen. Elizabeth Warren (D-Mass.) led the charge against the bill. She chastised fellow Democrats by name for backing proposals she said would put consumers at risk and undo key parts of the Dodd-Frank Act, the milestone 2010 law that imposed a raft of new regulations on banks.
“There are so many problems the American people are asking us to solve,” Warren said Wednesday. "But not one single person at any of my town halls, or meetings, or press interviews, or picking up pizza at Armando’s, asked for Congress to work on rolling back the rules on some of the biggest banks in the country so they’ll have a chance to crash the economy again.”
The issue exposed a deep rift inside the party as it struggles with a tug-of-war over what it stands for.
“It took a Republican majority with a Republican president for this bill to move because the core of the Democratic Party opposes these kinds of efforts to weaken Wall Street reform,” said Sherrod Brown of Ohio, who rallied opposition against the legislation as the top Democrat on the Senate Banking Committee.
The bill was the product of years of talks between Crapo and a core group of moderate Democrats: Heidi Heitkamp of North Dakota, Jon Tester of Montana, Joe Donnelly of Indiana and Mark Warner of Virginia.
The Democrats who drafted the bill, including several up for reelection in states that Trump won in 2016, argued that it was an example of Congress finally getting something done that would help the economy.
They tried to emphasize the benefits for the smallest lenders and their customers, particularly those in rural areas. They rejected attacks that the bill would blow a hole in regulatory oversight of the biggest Wall Street players.
“I don’t recognize the bill that’s being debated here in the United States Senate because it’s not the bill that’s been written,” co-sponsor Heitkamp said on the Senate floor Tuesday as she rebutted claims from Warren and others.
Without a doubt, the bill would have a broad impact on banks and consumers.
Included in the legislation: relaxed mortgage regulations for small banks; exemptions from stricter oversight for household-name firms like American Express and SunTrust with $50 billion to $250 billion in assets; and easier capital and liquidity requirements for several of the country’s biggest financial institutions, such as BNY Mellon and Citigroup.
Beyond the rollbacks, all consumers would be entitled to free credit freezes from credit-reporting companies like Equifax. Active-duty members of the military would get free credit monitoring. Another provision would establish new protections for veterans who refinance their mortgages.
While the bill is a huge victory for bank lobbyists who have been working to curb Dodd-Frank since it was first drafted, the industry will keep pushing lawmakers and regulators for carve-outs in the years to come.
"This is a first step," American Bankers Association President and CEO Rob Nichols said.
The White House has signaled that Trump would likely sign the bill, after he promised to scale back the Dodd-Frank law, one of former President Barack Obama‘s biggest achievements.
But despite the widespread political support for the legislation, the path forward through the House was unclear.
Hensarling, the House Financial Services Committee chairman, has brushed off the idea that the House GOP will simply accept the Senate’s legislation — raising the likelihood of a showdown that could drag on for months.
An outspoken free-market conservative, Hensarling is set to retire at the end of this Congress with a reputation for sometimes favoring ideology over pragmatism, even if it means being rolled by fellow Republicans.
He has spent years since the passage of Dodd-Frank advancing deregulatory bills through the House, including his sweeping Financial CHOICE Act that Republicans passed last year without a single Democratic vote.
But over the last several months, he has put an emphasis on moving bipartisan legislation, including some proposals that have the backing of liberals such as Rep. Maxine Waters of California, the top-ranking Democrat on his committee. (Waters opposes the Senate bill.)
As it became clear last week that the Senate would not incorporate more of the bipartisan bills he has ushered through the House, Hensarling circulated a list of some 30 proposals he wanted to be considered before the package went to Trump.
“There’s not a Dodd Act or a Frank Act,” Hensarling said Wednesday morning. “There’s a Dodd-Frank Act because the House went to conference with the Senate."
Hensarling’s pledge to keep tweaking the legislation is presenting an opportunity for lobbyists who were dissatisfied with the Senate compromise — including those working for large banks and insurance companies.
But it has alarmed representatives from other financial institutions that got what they wanted in the bill and want it signed into law as soon as possible. Some said they will press the House to just take the deal the Senate is delivering.
“Based on my meeting with the president, based on my meetings with both the House and Senate, it seems like we have a good bill that could become law very quickly if House leadership would allow that to happen,” said Jim Nussle, a former House member who now serves as CEO of the Credit Union National Association.
In a statement Wednesday, the White House said the president looked forward to discussing further House revisions but that he wanted a bill on his desk "as soon as possible."
Senate Democrats who toiled for years to pass the bill are daring Hensarling to amend the legislation, which they say rests on a delicate political foundation.
They say they have no expectation of having to vote on the bill again — a projection that, one way or another, Hensarling will fail as he makes one last stand to cement his legacy.
“It’s unfortunate,” Tester said. “If he adds a bunch of crazy shit, it’s going to die. That’s just the way it is.”
https://www.politico.com/story/2018/03/14/senate-passes-bill-scaling-back-dodd-frank-463825
Tags

Yes, that was the same excuse the pro-banks used to remove the banking regs (put in after the depression to make sure it wouldn't happen again) during the Clintons' adm.
Or....it might possibly have been argued that US banks had to deal with regulations that European banks did not, and therefore the European banks were kicking the crap out of their US counterparts.
My grandfather had a saying, "there's the way things should be, the way things could be, and the way things are, But to line up all three at the same time seems to be impossible."
We have the "should" and "could" figured out, but the "way things are" is all messed up. It became obvious where Politicians stood when they voted in "Citizens United" which has very little to do with normal citizens OR any form of uniting but has a lot to do with getting more money even from undisclosed sources.
Well, it isn't over yet, and maybe we can still clean this mess up if we vote in a mess of new people to office.
Most of the politicians we have now aren't worth the litter in a cat's box.
It became obvious where Politicians stood when they voted in "Citizens United"
What do you mean by politicians voting on "Citizens United" ?
What do you mean by politicians voting on "Citizens United" ?
I do not know what he meant but anyone not voting to overthrow Citizens United supports multi-national corporations purchasing our Republic. Once Citizens United allowed unlimited foreign corporate influence in our political process the multi-national corporations proceeded to do exactly that as evidenced by the advent of Trumpism which will be recorded ignominiously in history along with a lot of other misbegotten failed isms. By neutering Dodd-Frank the gop along with some democrats who are also in league with the big banks are setting up, again, the exact sort of deregulated banking situation that caused The Great Recession!
The Republican banking bill passed in a 67-31 vote, despite the opposition of Democrats like Sen. Elizabeth Warren. Advocates argued the Obama-era Dodd-Frank rules imposed an undue burden on small banks.
Yes, that was the same excuse the pro-banks used to remove the banking regs (put in after the depression to make sure it wouldn't happen again) during the Clintons' adm.
Gee, I hope the U.S. has good world credit, so we can barrow the money to bail the banks and the Nation out again.
Of course, ultra-cons seem to LOVE the idea of everybody (but themselves, of course) going through a great depression. It keeps poor people in line and grateful to work any jobs for crumbs and lets the wealthy buy up property and goods at bargain prices to rent out or sell later. Cheap goods to sell overseas too. It makes their money so much more valuable, what matters above that?
That's an interesting version of what happened in 2008. How about the Federal government forcing banks to degrade lending standards so that people who simply couldn't afford a home could buy a home they would eventually not be able to pay for?
One of the problems with Dodd-Frank aside from it's over-regulation was the problem of small banks inability to vet all the regulations and remain solvent. It actually made the big banks stronger.
No one held a gun to the banks heads and made them give those loans out, that law merely allowed them the opportunity to give loans to lesser qualified families if they wished. The greed of the banks was their own downfall, they did not manage their loans appropriately and handed out mortgages like water. All they could see was $$$$
the Community Reinvestment Act of 1977 (CRA), required all insured banks and S&Ls to make loans to borrowers at or below 80 percent of the median income in the areas the banks service. If these loans were profitable, of course, there would be no reason to require by regulation that they be made.
I disagree with you on that DRHunk. The banks were pretty much forced to provide those loans. There were many protest in front of Bank Presidents homes who tried to manage their loans to pass them out like flyers. Freddie Mac and Fannie Mae guaranteed them even though they knew most of them were worthless and very high risk. Then when the crap started hitting the fan after Frank Raines and company had made a fortune, the Democrats cried Racism when they wanted to tighten up the regulations.