
Cognitive Dissonance Alert! There's the daily dataflow and the ongoing crazy. Do not conflate the two

Category: Stock Market & Investments
Via: bob-nelson • 9 months ago • 1 commentsBy: Jared Bernstein

There's the daily dataflow and the ongoing crazy.
Do not conflate the two
Trump official allies with Europe’s far right in attacks on migration and hate speech policies
US state department’s Sarah B Rogers has become face of White House’s hostility to European liberal democracies
Jason Wilson
Don Lemon hires federal attorney who quit over handling of inquiry into Renee Good’s killing
Ex-CNN anchor brings on Joseph H Thompson to defend him from charges related to coverage of a church protest
Victoria Bekiempis
Trump orders Pentagon to buy electricity generated by coal
Trump’s order is the latest move by US administration to boost fossil fuel industry despite climate change concerns
John Power
Trump official overruled FDA scientists to reject Moderna’s flu shot
FDA’s top vaccine regulator, Vinay Prasad, is known for overruling scientists
Beth Mole
Joe Rogan Thinks People Are Not Allowed To Leave Oxford, England
People are allowed to leave Oxford, England
Robyn Pennacchia
The Racist Protector of Rapists
A million mentions in the Epstein files and counting
Mary L Trump
Minneapolis showed us why Trump and his fascists will lose
Lucian K. Truscott IV
February 12, 2026
Heather Cox Richardson
Pete Hegseth So Good At Job. Tabs, Fri., Feb. 13, 2026
Morning news roundup! Things to read!
Rebecca Schoenkopf
Fox News Pretty Sure ‘Shrieking Karen’ Pam Bondi Should Smile More
And that is what Fox News thinks about Pam Bondi
Evan Hurst
A Vote for Republicans Is a Vote Against Democracy
Can we reject the politics of concentration camps, election denial, and oligarchy by showing up in numbers too large to ignore?
Thom Hartmann
Maybe Russ Vought Wouldn't Need The Bodyguards If He Spent This $15 Million On Food Instead
Cause, meet effect.
Gary Legum
February 13, 2026
Heather Cox Richardson
 S E E D E D C O N T E N T
We’ve had a few good, if mixed, data reports in recent days. January jobs came in above expectations, and, more importantly (because the signal is better), unemployment ticked down. January inflation came in slightly below expectations. More broadly, fragilities abound but the macroeconomy is kinda okay, if not kinda good, especially if you consider productivity, which is a bit of a holy grail in my world.
But the country is being run—extremely poorly; see the current gov’t shutdown—by what I’m highly confident historians will rank as the worst administration ever to step foot in the White House. State sanctioned killings have yet to be accounted for. They’ve made the budget path even less sustainable. With affordability/cost-of-living challenges bedeviling American households, their signature economic policy—sweeping tariffs—is raising prices.
I’ve long written about this bifurcation, pointing out that in good times, presidents don’t have that much to do with overall growth, though they can skew its distribution. But today, I’d like to drill down on the connection between the monthly data, which I admittedly obsess over, and the broader political economy questions which dominate this Substack.
BLUF, they’re connected, but quite loosely. And understanding that loose connection is key to resolving the cognitive dissonance that can take hold around data releases.
First , given the intense focus by economists, markets, the Fed, and the media on the big econ reports, it is challenging though essential to always remember that one month does not a new trend make .
I’m always saying that but it hit me that this begs the question: “okay, then what does a new trend make?!” The circular answer is “a different trend.” The slightly more satisfying answer is enough months and quarters of the data moving in a different direction such that the underlying trend—which can, to be clear, be measured—shifts up or down.
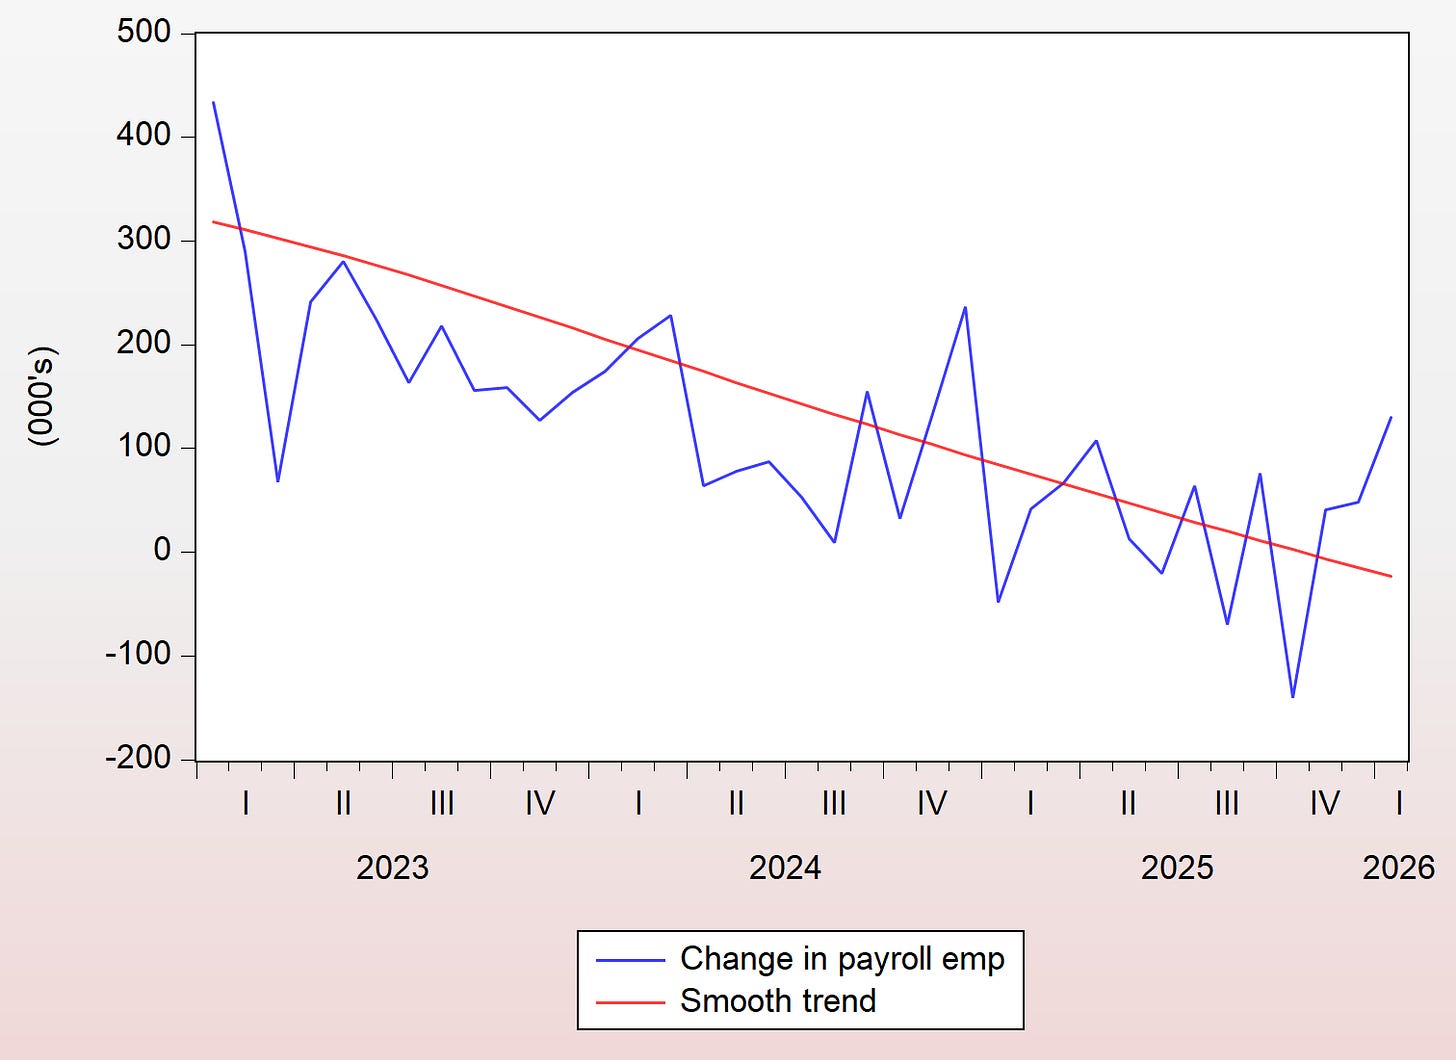
Let’s use the latest jobs report, with its upside surprise of 130K jobs as an example. The below figure shows monthly (not quarterly; didn’t bother fixing x-axis label) changes in employment around a slow-moving trend (a boosted HP filter, if you’re interested ). You see lots of monthly reports that are both above and below trend, with the latest read a clear, upside print. That’s definitional: trends by definition cut through points above and below the trendline. But the negative trend is clear (and, as noted below, became considerably more negative due to revisions).
So, what nudges a trend to switch direction? Enough observations broadly moving in the other direction, as occurred coming out of the mild 1990-91 downturn, shown below.
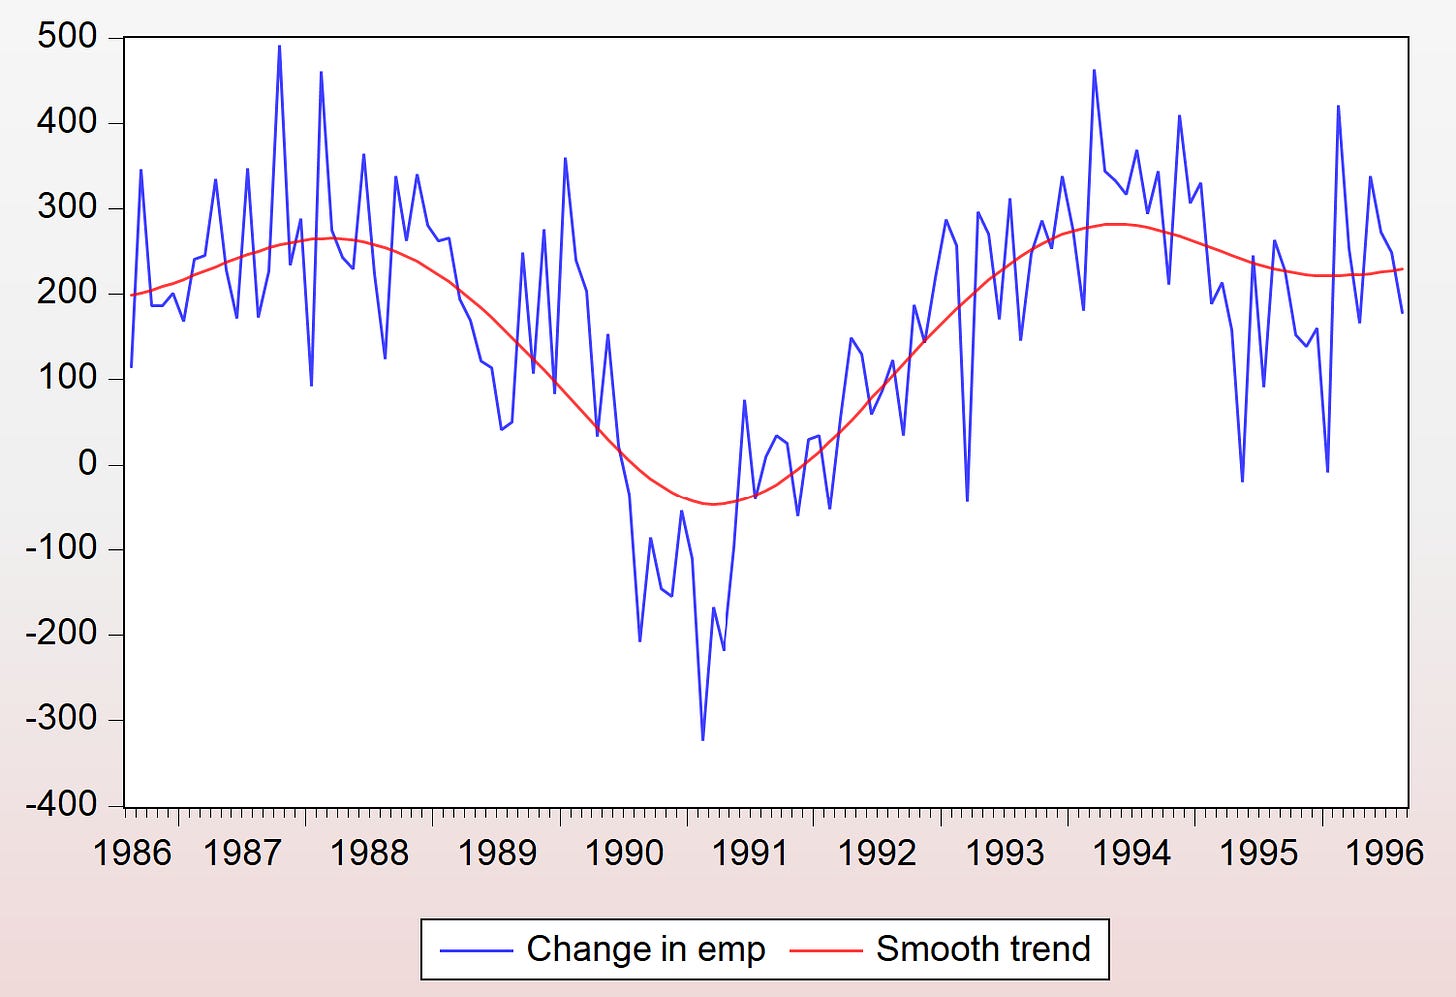
As high-frequency data analysts, we would be remiss to ignore the outliers above and below the trend, but they don’t change the story, which right now is of a labor market that has softened in a particularly troubling way: very low hires. I get into why that’s troubling here .
The other reason to underweight monthly observations is that in many series, they get revised, and job revisions have been especially sizable lately (why that is goes beyond my scope here; residual pandemic distortions and, esp re jobs, changes in immigrant flows are both in play).
Second , in trying to parse out how people feel about the data—econovibes—from the data itself, you’ve got to understand what the specific data series means to people.
Inflation is an extremely salient example. Ever since the pandemic price shock, people became highly uncomfortable with price levels, as distinct from price changes, i.e., inflation. Thus, when you tell them “inflation came in below what we expected,” as was the case with the January headline number, it just means prices are still going up, just the slightest bit slower than we thought (2.4% instead of 2.5%!). That’s important for economists, markets, the Fed—it’s comforting for us to hit expectations because it implies we kinda understand where we are—but it’s far too aggregated to mean much to everyday folks.
For them, the fact that beef and coffee are up 17% and 18%, respectively, and unleaded gas is down 8% matters a lot more.
GDP is another great example. It means a lot that same group noted above—economists, markets, Fed—but, as long as it’s not tanking, it’s far too aggregated and abstract to mean much to folks, especially when K-shaped dynamics are in play, as is the case now, as best we can tell. If overall growth isn’t reaching folks, we should they get excited about it?
Third , the cognitive dissonance is immediately amplified by the partisan media machine and the administration itself , and not just the Trump admin but all admins. I’ve been an offender in this space, and while I’ve always emphasized the trend points above, just the fact that you’re out there on WHNL (White-House-North-Lawn), going on about how we just added 200K jobs last month or inflation fell by a tenth or GDP rose by 2% annualized, etc., and how this shows the president is awesome, is a pretty unfortunate state of affairs.
At this point, I doubt anyone takes such noise very seriously, which is too bad, because, much as it’s important for the Fed chair to explain to the public what they’re up to, it is important for gov’t economists to explain to interested parties how their interventions are playing out. But you don’t get that from a monthly or quarterly data point.
In fact, you can learn more from longer-term analysis, such as the annual poverty reducing effects from the Biden-era expansion of the Child Tax Credit, or the eventual boom in factory construction from the various industrial policies that President Biden helped legislate. Or the increase in prices from Trump’s tariffs:
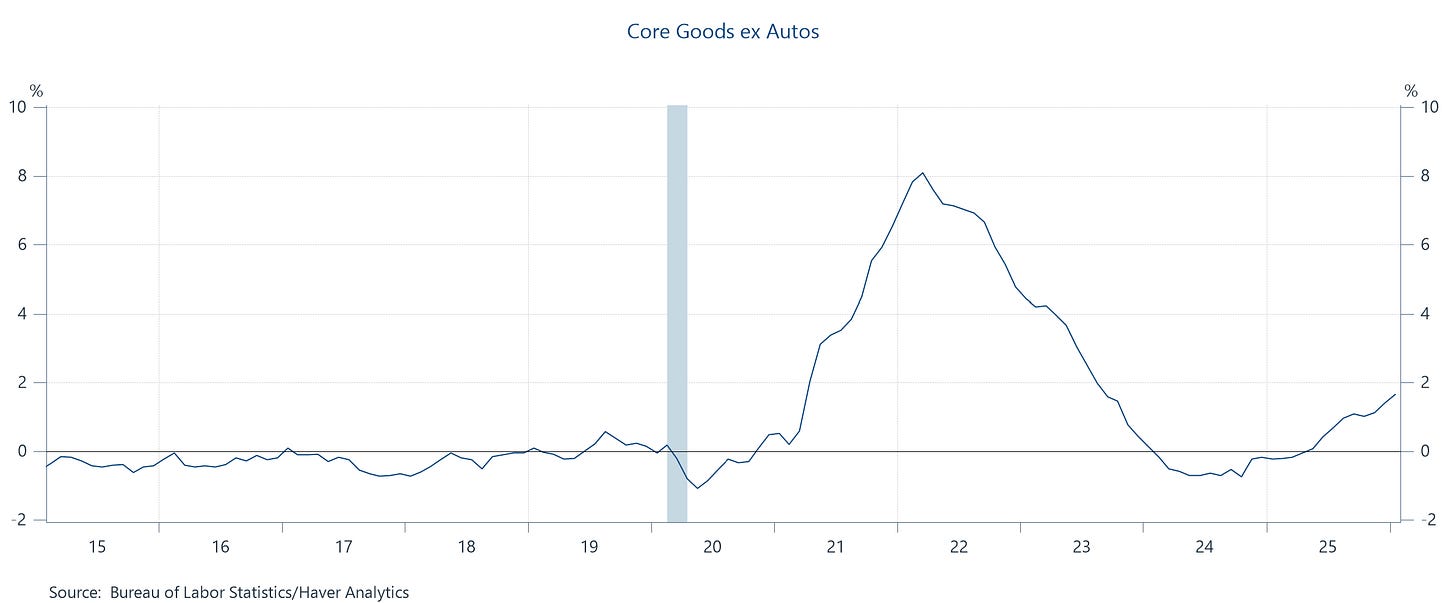
Right now, economic vibes are notoriously bad, and also pretty durably unresponsive to data reports one way or the other. As I recently stressed , people are increasingly put off by the chaos of the Trump administration and its lack of attention what’s really bugging them, particularly in the affordability space.
At the same time, for this Substack, I will continue to report on the dataflow as objectively as I can. This is just a reminder not to overly conflate the two.
Whatever
Tags
Who is online
86 visitors
Even if you don't care for economics, you should read this. It clarifies the apparent contradiction between those two quoted sentences. And how you can track both subjects.