
More Than 1 Million to Lose Obamacare Plans as Insurers Quit

A growing number of people in Obamacare are finding out their health insurance plans will disappear from the program next year, forcing them to find new coverage even as options shrink and prices rise.
At least 1.4 million people in 32 states will lose the Obamacare plan they have now, according to state officials contacted by Bloomberg. That’s largely caused by Aetna Inc., UnitedHealth Group Inc. and some state or regional insurers quitting the law’s markets for individual coverage.
It may also mean that instead of growing in 2017, Obamacare could shrink . As of March 31, the law covered 11.1 million people ; an Oct. 13 S&P Global Ratings report predicted that enrollment next year will range from an 8 percent decline to a 4 percent gain.
Vanishing Plan
Last year in Minnesota, Theresa Puffer, 61, used Obamacare to sign up for a BlueCross BlueShield plan after leaving her job following a skin cancer diagnosis. “I would have had a hard time finding any sort of coverage before the ACA,” Puffer said by phone.
Next year, Puffer’s plan is disappearing from Obamacare -- making her one of about 20,000 Minnesotans in the same situation. To make matters worse, premiums for other plans in the state will rise by at least 50 percent, though subsidies under the law can help cushion the blow.
“Trying to determine which would be the best plan for my situation is not easy,” Puffer said. Her dermatologist appears to be out of network in other plans, she said. “I’m willing to pay a higher premium to see him, because when you have cancer you want to stay with the same group of doctors,” she said. “I’ve spent so much time trying to figure out what my options are.”
Bloomberg contacted officials in all 50 states and Washington, D.C., and the 1.4 million-person estimate includes 32 states and only plans sold on the individual “exchange” markets. In Texas, Arizona, Georgia and Missouri, insurers have pulled out, but regulators couldn’t or wouldn’t say how many people are affected. Three states didn’t provide sufficient data.
Eleven states said they weren’t affected. In Washington, D.C., because one insurer withdrew some of its offerings, about 7,800 customers will need to choose new plans.
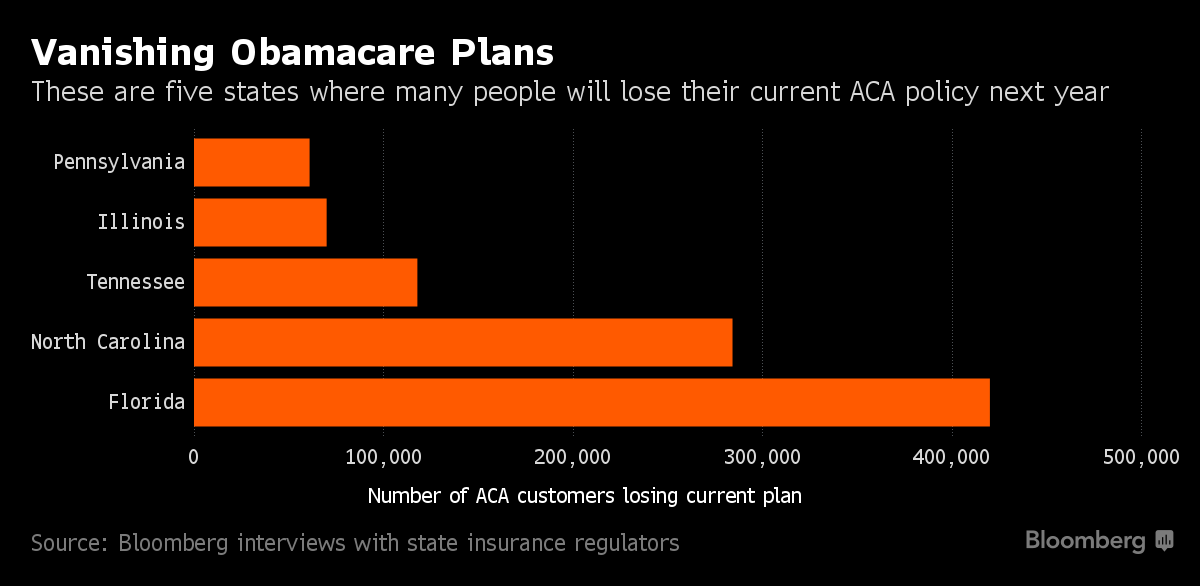 https://assets.bwbx.io/images/users/iqjWHBFdfxIU/ioaVQ7qMwDAo/v2/628x-1.png 628w, https://assets.bwbx.io/images/users/iqjWHBFdfxIU/ioaVQ7qMwDAo/v2/750x-1.png 750w, https://assets.bwbx.io/images/users/iqjWHBFdfxIU/ioaVQ7qMwDAo/v2/-1x-1.png 1200w" width="1263" data-attachment-key="305237033">
Normal Disruption
The U.S. agency that oversees Obamacare has said that some disruption is normal, and that choosing a new plan can help people get the best deal.
“It’s part of the normal business cycle for insurers to discontinue, change, and replace plans from year to year,” Benjamin Wakana, a spokesman for the Department of Health and Human Services, said by e-mail on Oct. 5. “Such changes don’t prevent people from obtaining coverage. People can shop for new coverage through a transparent market.”
HHS said Thursday that it will contact people losing their coverage and encourage them to sign up with new plans. The law requires all Americans to have insurance or pay a fine.
Nationwide estimates of the number of people losing their current plans are higher. For example, Charles Gaba, who tracks the law at ACASignups.net, estimates that 2 million to 2.5 million people in the U.S. will lose their current plans, compared with 2 million a year ago. Gaba’s estimate is based on insurance company membership data.
Fewer Choices
For the people losing plans, there are fewer and fewer choices. One estimate by the Kaiser Family Foundation predicts that for at least 19 percent of the people in Obamacare’s individual market next year there will be only one insurer to choose from.
In North Carolina, for example, a BlueCross BlueShield insurer will be the only option in 95 of the state’s 100 counties after Aetna and UnitedHealth said this year that they would leave. That will leave 284,000 people looking for a new plan, according to the state.
“Without any significant statutory and regulatory changes on the federal and state levels, we may face the crisis again,” said North Carolina Insurance Commissioner Wayne Goodwin, a Democrat who’s up for election this year. “There needs to be a wholesale re-evaluation by leaders in Washington.”
Losing Access
In Tennessee, UnitedHealth and the state’s BlueCross BlueShield plan are pulling back, and about 117,000 people will lose the plans they have now.
Amanda Page Cornett , a 34-year-old musician and athletic trainer in Nashville, is among them. For 2015, Cornett was careful to pick a BlueCross BlueShield plan that covered specialists at Vanderbilt Health, to treat nerve pain stemming from a 2013 accident. Her condition worsened recently, she said, and she’s worried about losing access to her doctor.
“I’m hopeful that he’s going to be able to help me,” she said of her current physician. “I feel like now I have two and a half months to figure it out before they shut me out.”
Tags
Who is online
93 visitors
Somebody tell me again how great Obamacare is.
You have to pass it first. Hey, wait a minute!
Here is the graph that got cut off above :
Maybe it's time for America to join other civilized western countries and institute a single payer system, so that there are no illness-caused bankruptcies, people unable to afford health care, etc.
We are voting on it here in Colorado and I'll be voting against it. It is projected to fail here. The answer to government failure is not more government.
Since our Amendment 69 survey in January, voter opposition has increased by 15 points from 50% to 65%. Support for the amendment has also declined 16 points, going from 43% to 27%. These findings are not that surprising considering Colorado’s history of rejecting large tax increases. We believe the amendment asks too much from Colorado voters by asking them to raise their state income tax by 10%. While the dream of universal healthcare may sound appealing to some Colorado voters, two thirds are unwilling to pay up for it.
How does a 10% income tax increase (and should I assume that is a percentage of the tax rather than a percentage of the taxable income) compare with the premiums and all costs of a comparable (equal services) commercial insurance coverage, or whatever it is that you have now? In Canada I could go to my own choice of doctor, a clinic, see a specialist, stay in a any hospital and have brain surgery and a heart replacement, and pay NOTHING.
All indications are the cost to the taxpayer would be more than he is paying now and doctors would pack their bags and leave. There is hardly any support for the measure here. We have a lot of deadbeats so the working man would get stuck paying for the deadbeats just like Obamacare.
If the plan were federal, universal, where would the doctors go? If the plan paid them what they were worth is that not enough? I can see them leaving if Colorado were the only state to use the plan - especially if they aren't altruistic.
Did you ever watch the movie "Doc Hollywood" with Michael J. Fox?
It's a disaster. At some point, the Obamaphiles are going to have to deal with the reality of the situation.
I work with low income seniors (in Michigan) and all of the people that have BCBS will see their premiums increase from $122.86 to over $255 a month next year...more than double!! That's on top of the $105 a month for Medicare. These are people whose incomes are generally less than $15,000 a year! Plus they have to get Part D Rx coverage or they're penalized.
It's disgusting...really.
And the higher income people are getting burned even harder due to the subsidies.
It is disgusting, the most disgusting part is that everyone including BO knew this would happen. Actually ESPECIALLY BO and his team that made this mess. Calling it the "Affordable care act" when 85% of Americans need financial assistance to be able to "afford" it should have been everyone's first clue that this program is totally unsustainable They all knew it would implode and that was the plan all along. Implode health care and usher in single payer while the system is in pandemonium and people are scared just like they did with the Patriot act. It is a shitty way to govern and causes untold suffering.
I can only imagine what will happen when a dysfunctional government takes over 20% of GDP.
I think that we should have a single payer system.
Do you think doctors should earn half as much like they do in France or people would want to stay in hospital wards instead of private rooms? The negatives of single payer need to be examined. It also does nothing to prevent a deadbeat from sucking off the productivity of the working man. When you look at the average profit of insurance companies it is only about 4% to 6% and they employ a lot of people. The cost of incompetent government taking over would surely be even higher as there would no longer be incentive for competitive advantage. Creating a monopoly run by the government is sure to fail.
It works well in Australia where you can have an outside policy if you chose to Dean.
There is no shortage of doctors to see there. I'm actually speaking from experience of having lived in Australia.
And having the experience of living most of my life in Canada, I can say that the health care system there works just fine. The Plan may just pay for a hospital ward bed, but anyone who earns a living income can afford a policy like Blue Cross to pay for extra charges for a private or semi-private room, as I had done when I needed it. Sure, it's true that some high-priced specialists left for the USA so they could charge exorbitant fees for their services, but enough stayed with the system. The GP I had lived a very comfortable life in a beautiful big home in a superior district with a couple of cars, a summer cottage, and kids going to private schools. I could choose my doctor, and upon his advice when necessary go to the best hospital for the service required. I don't think the American situation allows for that.
This is a real mess. Democrats passed Obamacare with no Republican support so they own the problem. Republicans have no incentive to help save it. To me, the basic premise of Obamacare was faulty from the beginning. The assumption was that the young would voluntarily enroll to help offset the costs for the sick. That didn't happen. The sick enrolled because they need help but the young avoided it and paid the fine because the fine was less than the coverage. To the young who are healthy (my son included), they saw no reason to pay for routine coverage when they would probably only need coverage in a catastrophe. In the event of a catastrophe, they could always enroll afterward and get covered. Meanwhile, they can spend their money on the really important things like having fun. If my son could figure this out, so could the Obama administration. This plan was doomed from the start because it depended on the young to spend money on health care they didn't need in order to subsidize the sick who needed coverage. Without the young contributing and to keep the subsidies for the poor going, the only option is to raise premiums on everybody else. The only way out (which maintains the concept of universal healthcare) is to move to single payer and that road may be blocked by Republicans standing with their arms folded saying "I told you this wouldn't work. Now let's try it my way."
Back when this Obamacare first started I remember a person around 60 would have a premium of around $8000 per year. A person making $35000 would only have to pay around $3000 of that amount for a 70% policy. That means $5000 would have to be subsidized. If that person increased their income by $10000 to $45000 they would have to pay the entire $8000, but the additional taxes on that extra $10000 plus the increase in premium would render almost all of the extra income as insignificant.
If the same person only made $20000 a year the 70% policy would be free to them, but the cost would still be $8000. When a person's income reached approximately $45000 their premium would include their cost plus all the cost for anyone making less that $45000.
I really don't want anyone to have to suffer without medical care. Unfortunately we will always have people who pay their way and people who don't or can't, but I believe we need to figure some way to make sure all regardless of whether they are able to care for themselves or unwilling to care for themselves have medical care, but it will come at a tremendous cost to all those who can least afford to pay that cost.
The very rich pay cash for their medical care and the cost couldn't even be considered pocket change.
The very successful but not as rich pay the premiums with their pocket change.
The next group of people below them are able to handle the cost without too much difficulty.
The majority of working Americans making $45000 will have a big chunk of their pay removed from their paycheck each month and they will have no other choice than to accept it. The IRS has already been able to make many people tax slaves to the state since Obamacare started by the fines or the increase in income making these people owe more at the end of the year than they paid, leaving them with debts they are unable to cover. I don't know for sure, but I would imagine they are now having those extra premiums removed from their checks each month plus the new higher premiums removed as will with single premium on the horizon.
For example a person starting the year out with a projected yearly income of $35000 paying $3000 for the year gets some nice pay increases and by the end of the year they are making $45000. Well they now have to pay $8000 for the coverage and owe up to $5000 in uncollected premium for the past year.
It is a mess. I don't see how a 10% increase of taxes could do it. I think it would require more like 25%. I don't know, but all the money that has been thrown out the window for a failed policy with zero support from its inception from the Republicans when at least a bi-partisan effort could possibly have saved some of the wasted money on far worse coverage than most of the people had before Obamacare.
The problem with the Affordable Care Act is that it relied on insurance to "make healthcare affordable". The problem is not insurance. The problem is the astronomical cost of healthcare in this country.
Here is an example:
My wife requires a bone shot each month. That shot cost $8000.00. My insurance authorizes the shot at $5000.00, and pays $4000.00, leaving me with a bill for $1000.00 per month for one shot. Now, the manufacturer has a program where they cover the entire cost share except $25.00. So in reality, my cost is $25.00. But WHY? Why does the manufacturer eat $975.00 of the cost? And what about the other $3000.00 difference between what my insurance company allows, and what the clinic charges?
We see this all the time in our Explanation of Benefits. A procedure is charged at $10,000.00, but the insurance only allows for $4000.00. Some would say, "Look, your insurance has saved you money, by reducing the cost of the procedure." No, the question should be if the clinic accepts $4000.00 as payment for a billed $10,000.00 procedure, why is the procedure $10,000.00 in the first fucking place?
I feel like doctors are the new mob. "You like your health?" is the new "You like those kneecaps?"
My wife requires a bone shot each month. That shot cost $8000.00. My insurance authorizes the shot at $5000.00, and pays $4000.00, leaving me with a bill for $1000.00 per month for one shot. Now, the manufacturer has a program where they cover the entire cost share except $25.00. So in reality, my cost is $25.00. But WHY? Why does the manufacturer eat $975.00 of the cost? And what about the other $3000.00 difference between what my insurance company allows, and what the clinic charges?
Thank you ! Your post clearly illustrates the insane chaos in our healthcare industry. I signed up for Obama care a year ago. I was so happy because health screenings would be totally free. Except they are not. If something questionable is found in your screening the provider has to by law code the procedure as "diagnostic" and not "preventative" (free screening). So if something is found in my screening it jumps from "free" to $6000. I currently pay cash for screenings as the costs are about 80% cheaper than what insurance companies bill.
The one reason left for me to keep this policy is because if I had a traumatic injury I would have a choice as to where the ambulance would take me. No insurance, no choice. That's enough to keep it for now.