╌>

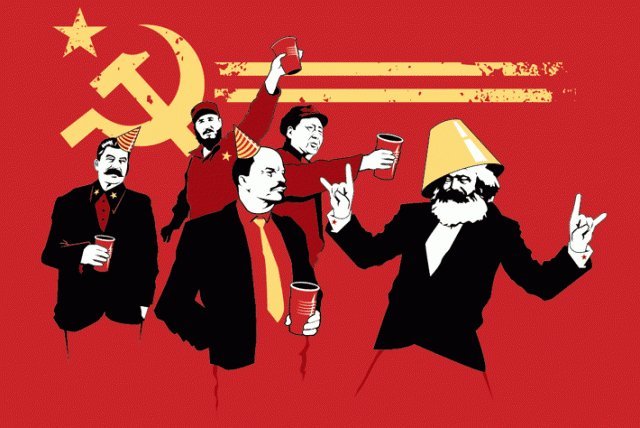
Commie commie commie commie commie K-Keynesian

  

Category:  News & Politics

Via:  bob-nelson  •  12 years ago  •  14 comments

Commie commie commie commie commie K-Keynesian

Commies+awesome+printing+on+t+shirt+credits+to+whoever+made+this_88d211_4026049.jpg?width=400

Boy, do people like arguing over whether "Keyneisanism" is right or wrong.
I suspect that much of the motivation for John Cochrane to write this latest blast comes from his ongoing personal feud with Paul Krugman , generally acclaimed as the champion of "Keynesianism". Of course, the Wall Street Journal eats it up, since to most WSJ readers, "Keynesian" is a code-word for "commie" (thanks, Friedrich Hayek). The result of these two forces is an article which has a few good points buried deep inside it, but which is mostly wrong.
This seed is for economics wonks. For them, it is hilarious.
For anyone else... it's incomprehensible.

Commie commie commie commie commie K-Keynesian


Tags

jrDiscussion - desc
[]
 
Bob Nelson
Professor Guide
link   seeder  Bob Nelson    12 years ago

Cochrane is at something of a disadvantage in his slugfest with Krugman. He has no idea what Keynesianism actually means.


Petey Coober
Freshman Silent
link   Petey Coober    12 years ago

Of the 2 major economic theories from Keynes & Hayek , each of them works at times but not at other times .


Bob Nelson
Professor Guide
link   seeder  Bob Nelson    12 years ago

I don't read porn.

68.gif 68.gif 68.gif


Bob Nelson
Professor Guide
link   seeder  Bob Nelson    12 years ago

Austrian Economics

Contradiction in terms.


Len
Freshman Silent
link   Len    12 years ago

What is YOUR eco background, smarty pants?

Here is your "expert:"

Noah has been a finance professor at SUNY Stony Brook, an economics PhD student at the University of Michigan, an academic editor in Japan, and a physics major at Stanford. He is currently hard at work on solving all the problems of the world. So don't be surprised when all your problems suddenly vanish. It was Noah.

Jack of all trades, master of none. Notice that he was an "economics PhD student" and "physics major"but nothing about any degrees. OTOH:

Mr. Cochrane is a professor of finance at the University of Chicago Booth School of Business, a senior fellow at Stanford Universitys Hoover Institution and an adjunct scholar at the Cato Institute.

"Is," not "has been." Whatgrade of professor was Noah? What is he now besides a blogger?

Was this your comment in the Journal?

Bob Nelson subscriber 11 hours ago

Imagine a small valley with 3 wolf packs of which two, A & B, operate under rules of the animal kingdom and the third, C, has a number of sick, ailing and old wolves who have voted themselves half the food caught by the pack. Each pack has six female and six male wolves and every female has 4 pups every year, thus every year the 3 packs increase exponentially by factors of the first year's 72 offspring, but the small valley can only support 36 wolves.

Like the wolves, we humans are predators and yet we have a political system that has evolved to take from the successful segment of our society, including those that saved,to give to another to get their votes. However, taking from the successful segment only works if it builds a future for all and is not squandered by shifting wealth. Our current administration's political system is called "Bread and Circus vote buying" and over the last 2200 years it has collapsed every Democracy, beginning with Rome.

This Bob Nelson appears to oppose Keynesianism.


sixpick
Professor Quiet
link   sixpick    12 years ago

Once the principle is admitted that it is the duty of the government to protect the individual against his own foolishness, no serious objections can be advanced against further encroachments.
Ludwig von Mises


Petey Coober
Freshman Silent
link   Petey Coober    12 years ago

You're off topic . Here's the topic :


Buzz of the Orient
Professor Expert
link   Buzz of the Orient    12 years ago

Commie commie commie commie commie K-Keynesian

Was that written by Boy George?


Bob Nelson
Professor Guide
link   seeder  Bob Nelson    12 years ago

smarty pants

OMG! That hurts so-o-o-o-o-o BAD!!

103.gif 103.gif 103.gif

Do you have anything substantive to say?


jennilee
Freshman Silent
link   jennilee    12 years ago
Must have been, because I was singing it in my head when I read the title


Bob Nelson
Professor Guide
link   seeder  Bob Nelson    12 years ago


Bob Nelson
Professor Guide
link   seeder  Bob Nelson    12 years ago

Noah Smith references Paul Krugman, of course. Krugman is Cochrane's bte noire . But Krugman is hardly the only vituperative Keynesian out there! Brad DeLong is kinda wicked:

If You Had Told Me Twenty Years Ago That the People the Wall Street Journal Put on Its Op-Ed Page Would Only Get Less Hinged as Time Passed...

I would not have believed you. But is is true.

And so I gotta ask: Does John Cochrane have no friends? It is intervention time here: Cochrane is doing himself and his reputation no good by this.

He ought to simply say that he was clearly underbriefed back in 2007-9 and said some stupid things, that he recognizes that the world has evolved since 2007 in ways strikingly inconsistent with the beliefs he had then, apologize, and go back to doing what he does (or perhaps used to appear to do) well, asset pricing, and do that well--if he still can).

His friends need to tell him this.

Frances Coppola is not his friend:

Frances Coppola : The Gullible Economist : "I think John Cochrane has lost his marbles...

..has written one of the worst op-eds I have ever seen... quotes George Osborne as an authority on.... Keynesian economics. You couldn't make it up. Cullen fisked about half the article but gave up in disgust when he encountered this little gem:

By Keynesian logic, fraud is good; thieves have notoriously high marginal propensities to consume.


Bob Nelson
Professor Guide
link   seeder  Bob Nelson    12 years ago

... And then there's Dean Baker: John Cochrane Versus the Keynesians, #23,127 :

I see that John Cochrane is once again attacking Keynesian economics, giving an autopsy for Keynesians in the Wall Street Journal. His central line is that Keynesian economics has been repeatedly proven wrong in the recovery. He sees the U.K.s turn to austerity as a brilliant success; and the continued U.S. growth, in spite of deficit reduction, as further proof of the failures of Keynesian economics. He tells us that even Greece and Italy are sticking with the euro, rejecting the course of devaluation and inflation.

I understand that Cochranes polemic is directed at Paul Krugman, but as a card carrying Keynesian, I will take up the defense. First, it requires some serious re-writing of history to pronounce the Keynesians wrong at every turn in this recession and recovery. Going back to the days of Great Moderation, some of us Keynesian types noticed the economy was being driven by a housing bubble long before the beginning of the Great Recession.

Im not sure where bubbles fit in Cochranes world, but in this economy they are run-ups in asset prices that are not consistent with the fundamentals of the market. In most cases they are not of great consequence for the economy as a whole, only for the markets directly affected. However when the market is a massive market, like the U.S. housing market, and the bubble grows to the neighborhood of $8 trillion (@ $10 trillion in todays economy), it is a big deal. The housing bubble raised residential construction to a record share of GDP. The associated wealth effect led to a huge consumption boom with the saving rate pushed to a record low.

When the bubble burst, there was no component of GDP that would magically replace these sources of demand. The outcome was a severe recession. The real world followed pretty well on this Keynesians line of thinking.

Cochrane somehow thinks the Keynesians blundered in believing that the stimulus would set everything right:

Our first big stimulus fell flat, leaving Keynesians to argue that the recession would have been worse otherwise.

Well, some of us were arguing at the time that the stimulus was far too small to get the economy back on its feet, so we were hardly surprised when our prognostications proved correct. (Krugman made the same case in a far more visible forum.)

Cochrane then adds:

With the 2013 sequester, Keynesians warned that reduced spending and the end of 99-week unemployment benefits would drive the economy back to recession. Instead, unemployment came down faster than expected, and growth returned, albeit modestly.

For my part, I never saw a recession, just weaker growth. The GDP data seem to agree with me. Growth in the first two quarters of 2013 was just 2.3 percent. If we just look at final demand (excluding the buildup of inventories), growth averaged 1.8 percent in the first half of 2013. While the unemployment rate did fall by 1.2 percentage points from December of 2012 to December of 2013, this was largely because of people leaving the labor force. The employment to population ratio did not change over this period. Should us Keynesian types feel embarrassed?

At this point there is considerable research on the impact of stimulus and most of supports the Keynesian story. (Here are a couple from the I.M.F . and a good meta-analysis from my friend Sebastian Gechert. Its not clear what real world evidence Cochrane thinks we should take as refuting the benefits of Keynesian stimulus.

Cochrane can be given partial credit for a mistaken prediction of some Keynesians:

Keynesians told us that once interest rates got stuck at or near zero, economies would fall into a deflationary spiral. Deflation would lower demand, causing more deflation, and so on.

Since all of us card carrying Keynesians are supposed to believe in sticky wages, it is not clear why any ever took seriously the idea of a deflationary spiral. After all, even Japan never saw its deflation rate exceed -1.0 percent for any substantial period of time. Some of us did try to point out that the obsession with deflation was misplaced, as the rest of the Keynesian clan eventually came to recognize.

Cochranes view of the U.K. as a success story that vindicates austerity also seems to fly in the face of the data. At the most basic level, the bottom line numbers are not especially inspiring. More than four years into the reign of austerity, per capita GDP in the U.K. is still 3.9 percent below its 2007 level. Thats considerably worse than the 1.9 percent growth in Keynesian (since 2013) Japan and even the 1.2 percent drop in semi-austerity France.

The modest turn-around the U.K. has achieved has been largely on the back of a new housing bubble, with inflation-adjusted house prices again approaching bubble peaks. This run-up is at least in part due to deliberate policy as the Conservative government gave a first-time homebuyers tax credit to boost the market.

Many of Cochranes other assertions just fly in the face of reality or deliberately distort what Keynesians say about the world. For example he has a tirade about the evils of debt:

Keynesians tell us not to worry about huge debts, or to default or inflate them away (but please, call it restructuring or repairing balance sheets). Even the Obama administration has ignored that advice, promising long-run solutions to the debt problem from day one. Europeans have centuries of memories of what happens to governments that dont pay debts, or who need to borrow for a new emergency but have stiffed their creditors once too often. More debt? Nein danke!

We have seen a huge run-up in debt since the downturn and yet long-term interest rates are for the most part at record lows. Japan, the most profligate spender of them all, now has to pay a usurious 0.34 percentage point interest rate on its long-term debt. Are we advocates of deficit spending supposed to see our argument refuted by this evidence?

He then complains that we see even wasteful spending as boosting the economy. Yep, thats true in a downturn, but we would all prefer useful spending. He challenges Keynesians:

Stimulus advocates: Can you bring yourselves to say that the Keystone XL pipeline, LNG export terminals, nuclear power plants and dams are infrastructure?

Umm, yes. I dont know any Keynesians who would dispute that this spending would provide a boost to the economy. The question is how large and at what cost. Sending in troops to raze Wall Street would also provide a boost to the economy. Is that worth the cost? (Okay, that was a bad example.)

At the end of the day, Cochrane can make a political argument. His team has won in convincing governments to go the route of austerity. Is this good? Well, the U.S. is still down close to 6 million jobs from its trend level. Greece is looking at double-digit unemployment for at least the rest of the decade. The story for other euro peripheral countries is not much better.

Why have political leaders opted to put their populations through hell? My answer is that the people who have the money it takes to finance elections, and also who control much of the media, are not bothered by the current situation. After all, the stock market has rebounded, their banks have been saved. Theyre doing just fine, even if the average French, Italian, or American worker is still faring badly.

Does that explanation work? Im open to other stories, but it is the political analysis where Cochrane may have a case against the Keynesians. His attack on the economics doesnt stand up to the light of day.


Bob Nelson
Professor Guide
link   seeder  Bob Nelson    12 years ago

... And Robert Waldman, On Smith On Cochrane On Keynesians :

Cochrane wrote With the 2013 sequester, Keynesians warned that reduced spending and the end of 99-week unemployment benefits would drive the economy back to recession. Instead, unemployment came down faster than expected, and growth returned, albeit modestly.

Exactly which Keynesians predicted that sequestration would cause a recession ? I think that as a matter of good editorial policy, names with citations in support of all such claims should be demanded (I am not saying the WSJ must publish the names, just that a competent editor should demand that the author prove that the author can name such names).

I note *again* that, there is no puzzle to Keynesians about why sequestration wasnt followed by a marked change in the growth path of GDP (let alone a recession). The reason is that sequestration did not cause a marked change in the path of US G real government consumption and investment. It was threatened in advance. It was a change to annual budgets which doesnt force a sudden shift in spending within the year. Much of G is state and local. It declined and declined, then increased. The rate of GDP growth is clearly correlated with G growth. Economists should look at such data before writing.

sequestration-300x183.jpg?width=350

Quick look at the graph (dont look at the x-axis) can you guess when sequestration started ?

Also note sequestration hit March 1 2013, extended unemployment benefits ended January 2014. Lumping them together is very casual data analysis. This is quite important because, when one considers state and local spending too, there has been constant anti-Keynesian austerity since ARRA stimulus spending peaked. Thus a stone Keynesian would predict consistently disappointing growth (at least until the past 2 quarters see the graph). This is exactly what happened (where disappointing means below Fed forecasts and that is just a fact).

Cochrane

The Phillips curve failed to understand inflation in the 1970s and its quick end in the 1980s, and disappeared in our recession as unemployment soared with steady inflation.

First does the WSJ employ editors ? Obviously a curve didnt understand. Understanding requires a brain. The Phillips curve is brainless. It is not the only brainless entity.

The Phillips curve was never Keynesian doctrine. The prominent Keynesians used expectations augmented Phillips curves which fit the data from the 70s and 80s well. The end of the US inflation included a huge recession. This fits the Keynesians story and not at all the Lucas supply function or RBC stories. In contrast, in Europe, the disaster which followed disinflation was almost as far from predictions based on New Keynesian models as from those based on new classical models. Cochrane is relying on false claims about intellectual history. To many links but google James Forder Oxford.

Or again, names and cites. He will not be able to cite a prominent Keynesian who said the expectations augmented Phillips curve is stable, because no such person exists. I count Phillips as a prominent Keynesian. They dont have Paris and never really did.


Who is online


Tacos!


60 visitors