
Krugman Twofer: A Liz Truss Moment for America? || Gaming Out a Sudden Stop


Financial indicators are flashing yellow
and
What happens if investors lose faith in America?
Data. Data. Data. And then more data.
I'm really pleased to see our MAGA members bringing their own "well-sourced" data to these conversations. 
A Liz Truss Moment for America?
Financial indicators are flashing yellow
Despite hitting a few speed bumps, Congress seems likely to pass Donald Trump’s “big, beautiful bill” — legislation that combines big tax cuts for the rich with vicious cuts in social programs — within a few days. This momentous move will take place with almost no public discussion; the final hearing of the House Rules Committee began at 1 AM this morning. That’s right, 1 AM. We’re clearly watching a bum’s rush, an attempt to ram this atrocity through before the public understands what’s happening.
I have already focused on the bill’s cruelty. It’s also deeply irresponsible, undermining America’s hard-won reputation as a country that honors its obligations. The cuts to Medicaid and food stamps won’t come close to offsetting the revenue loss from the tax cuts for the rich. Neither will revenue from tariffs. And can we all now acknowledge that DOGE’s promise to eliminate hundreds of billions in “waste, fraud and abuse” hasn’t just failed? It has ended up being a complete waste of time, which it has tried to conceal with fraudulent claims of achievement, all while abusing dedicated civil servants and driving them out of government in ways that will impoverish America in the long run — and maybe not that long. We’re a world leader in education, science and technology that is systematically destroying the very basis of our success.
So we’re looking at a large increase in an already high budget deficit when we’re already at full employment, interest rates are already at multiyear highs, and future growth prospects are declining.
Financial markets normally cut wealthy nations with stable governments a lot of slack, with reason. Rich, well governed countries have immense ability to raise revenues if needed, especially if, like the United States, you collect a smaller percentage of GDP in taxes than almost any other advanced economy:

In other words, until now markets have believed that the U.S. has the resources to deal with its deficit whenever it musters the political will. And bond buyers have been willing to assume that we are a serious country that will eventually get its fiscal house in order.
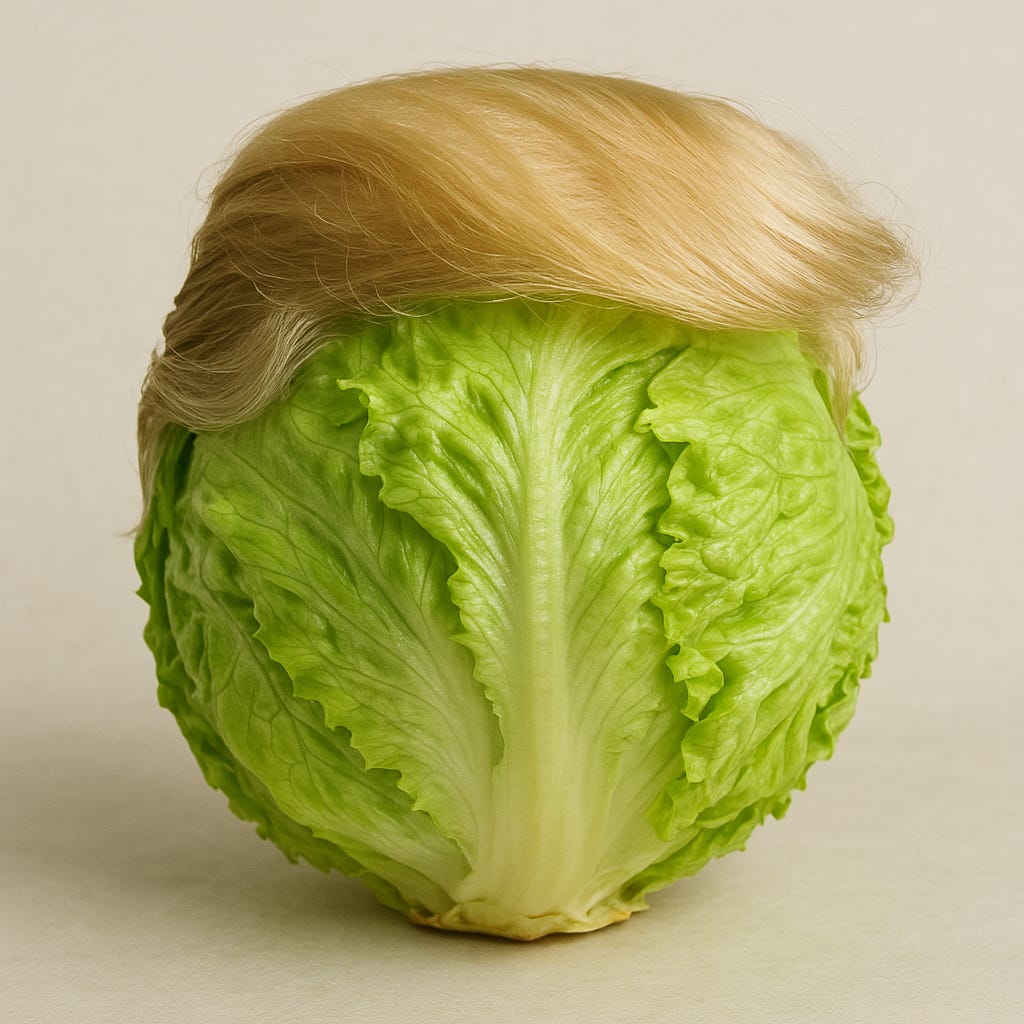
But markets’ patience with American dysfunction isn’t unlimited. Consider how quickly things went wrong for the UK. In 2022 Liz Truss , Britain’s Prime Minister, announced a “mini-budget” that involved cutting taxes and blowing up the budget deficit. Markets freaked out: long-term interest rates soared and the pound plunged. The tabloid The Daily Star famously set up a webcam showing a photo of Truss next to a head of iceberg lettuce wearing a wig, and asked which would last longer.
The lettuce won, because Britain’s parliamentary system allowed it to get rid of a disastrous leader. We, unfortunately, can’t.
So are we facing a Liz Truss moment in America? Long-term interest rates are close to their highest level in many years:

The dollar, which rose after Trump’s election, has now fallen sharply:

Source: xe.com
These market movements, especially in combination, are disturbing and at least hints that something like a Truss moment may be looming. We saw a whiff of that after Trump’s Liberation Day tariffs; what happens when markets realize that the budget is, in its own way, just as bad?
First, interest rates: deficit spending often does drive long-term interest rates up. But normally that’s because investors expect the spending to cause an inflationary boom, which the Federal Reserve will try to contain by raising short-term rates. That’s what happened when Ronald Reagan cut taxes while increasing military spending. Here’s an estimate of the real interest rate on 10-year bonds, where the real rate is the nominal rate minus expected inflation, which I proxy with actual core inflation over the previous year:

This time around most people expect the Fed to cut rather than raise short-term rates, because uncertainty over Trump’s tariff policies seems certain to cause an economic slowdown and possibly a recession. So why are long-term rates up?
Furthermore, a rise in U.S. interest rates normally causes the dollar to rise, as it did in the Reagan years. After all, higher rates should make investing in America more attractive, pulling in foreign capital and pushing the dollar up. But this time the dollar has been heading down.
So what’s going on? The Truss moment in Britain was partly caused by technical issues involving pension funds. But we may be facing technical issues of our own, especially involving hedge funds. In a larger sense Britain’s crisis was driven by a loss of credibility. Truss clearly believed in American-style voodoo economics, the belief that tax cuts have magical powers. Investors didn’t share that belief, so they effectively voted for the lettuce.
Unlike retail investors who are often driven by vibes, investment pros have clear doubts about Donald Trump’s credibility. The price of US credit default swaps — which are supposed to protect investors if America fails to honor its debt, and are an indicator of market pros’ sentiment — has surged:

Source: Worldgovernmentbonds.com
These market moves in bonds and swaps show that the Trump administration is losing credibility, just as the Truss government did. Professional investors are ceasing to treat us as a serious country.
Instead, they’re starting to treat us like an emerging market, where budget deficits are a sign that things are spinning out of control. This irresponsible bill is already being seen as a signal to sell America, leading to higher interest rates, increasing odds of a recession, and a weaker dollar. And the example of Britain shows that things could spiral out of control faster than almost anyone imagines.
Gaming Out a Sudden Stop
What happens if investors lose faith in America?
I used to be an economics ambulance-chaser — someone who raced around the world to wherever there was an interesting economic calamity. And this international experience probably made me more sensitive than most economists to the way economies that seem to be doing OK can suddenly fall off a cliff into economic crisis.
In 2008, of course, America had a financial crisis of its own — and it was a nightmare. But it was very different from the emerging-market crises I used to spend so much time on. And right now I’m worried that the U.S. might be facing an emerging-market-type crisis: A “sudden stop,” an abrupt cutoff of inflows of foreign capital. If we have a crisis like that it could, in particular, cause a severe housing crash.
I wrote a month ago about the possibility of a sudden stop for the United States. Despite growing pressure on both U.S. interest rates and the dollar, we aren’t there yet. I was, however, a disciple of the late, great Rudiger Dornbusch, whose students often quote Dornbusch’s Law :
The crisis takes a much longer time coming than you think, and then it happens much faster than you would have thought.
So a U.S. sudden stop still looks quite possible, indeed considerably more likely given the grotesquely cruel and irresponsible budget bill Republicans are trying to ram through. It doesn’t help that key players are being utterly dishonest about what they’re doing: House Republicans have been denying that the bill will increase the budget deficit, while Trump claims that “ We’re not touching anything ” on Medicaid, just eliminating waste, fraud and abuse (and somehow taking away health care for millions in the process.) Low-information voters may be fooled for a little while, but bond markets won’t.
But while I’ve already written about the possibility of a sudden stop, I haven’t said much about what such a stop, if it happens, would look like. So let’s game it out.
The starting point here is the fact that the United States runs persistent, large trade deficits:
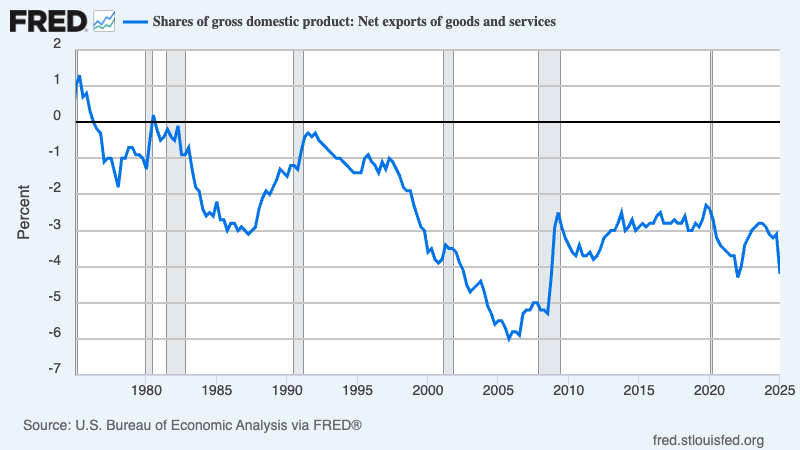
We’ve been able to cover these deficits painlessly because the world has been eager to invest in America, with large inflows of capital matching our deficit in goods and services. One consequence of decades of capital inflows, however, is that America owes a lot of money to the rest of the world. Here’s our net international investment position, the difference between U.S. assets abroad and foreign assets here, shown as a percentage of GDP:
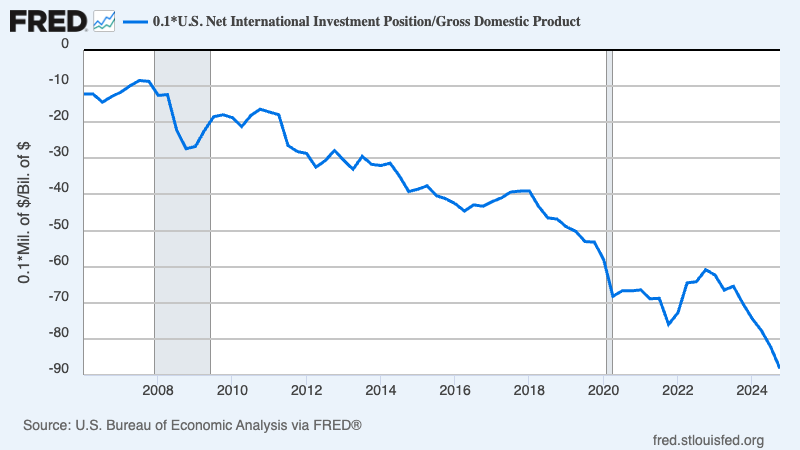
That’s a lot of U.S. debt held by foreigners! It hasn’t been a problem in the past because foreign investors have considered America a good place to put their money. But what happens if they change their minds?
A footnote: official numbers almost certainly understate how much America pays out each year to foreign investors, because of tax avoidance. Multinational corporations that earn profits in the United States use strategies like fictitious pricing and transfers of intellectual property to make those profits disappear here and reappear in low-tax countries like Ireland.
But the important point for now is that we have a big trade deficit covered by large inflows of capital, which in turn reflect the fact that foreign investors have considered America a good place to put their money.
And the question is what happens if investors change their minds — if they decide that we’re an unserious country in which the governing party believes in voodoo economics and the president is an authoritarian ruler who spends much of his time rage-tweeting about popular musicians.
A sudden stop to capital flows into America would mean that there would no longer be money to cover those big trade deficits — and this would mean a sharp drop in the foreign exchange value of the dollar. On the eve of its 2001 sudden-stop crisis Argentina had a trade deficit, as a share of GDP, similar to that of the United States now — and when the crisis hit the peso lost more than half its value. A U.S. sudden stop would probably be less severe because our foreign debts are overwhelmingly in dollars, which insulates us from some of the fallout Argentina faced. Still, this could be ugly.

The impact on interest rates could be especially ugly. The United States relies on inflows of capital from abroad to pay for a significant part of domestic investment spending:
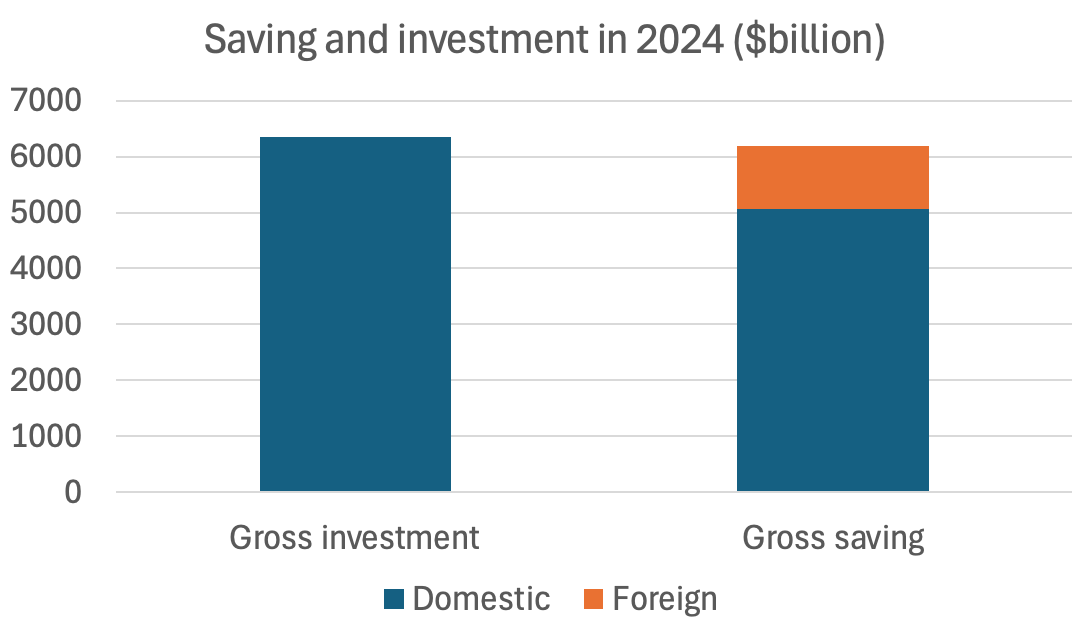
Source: Bureau of Economic Analysis
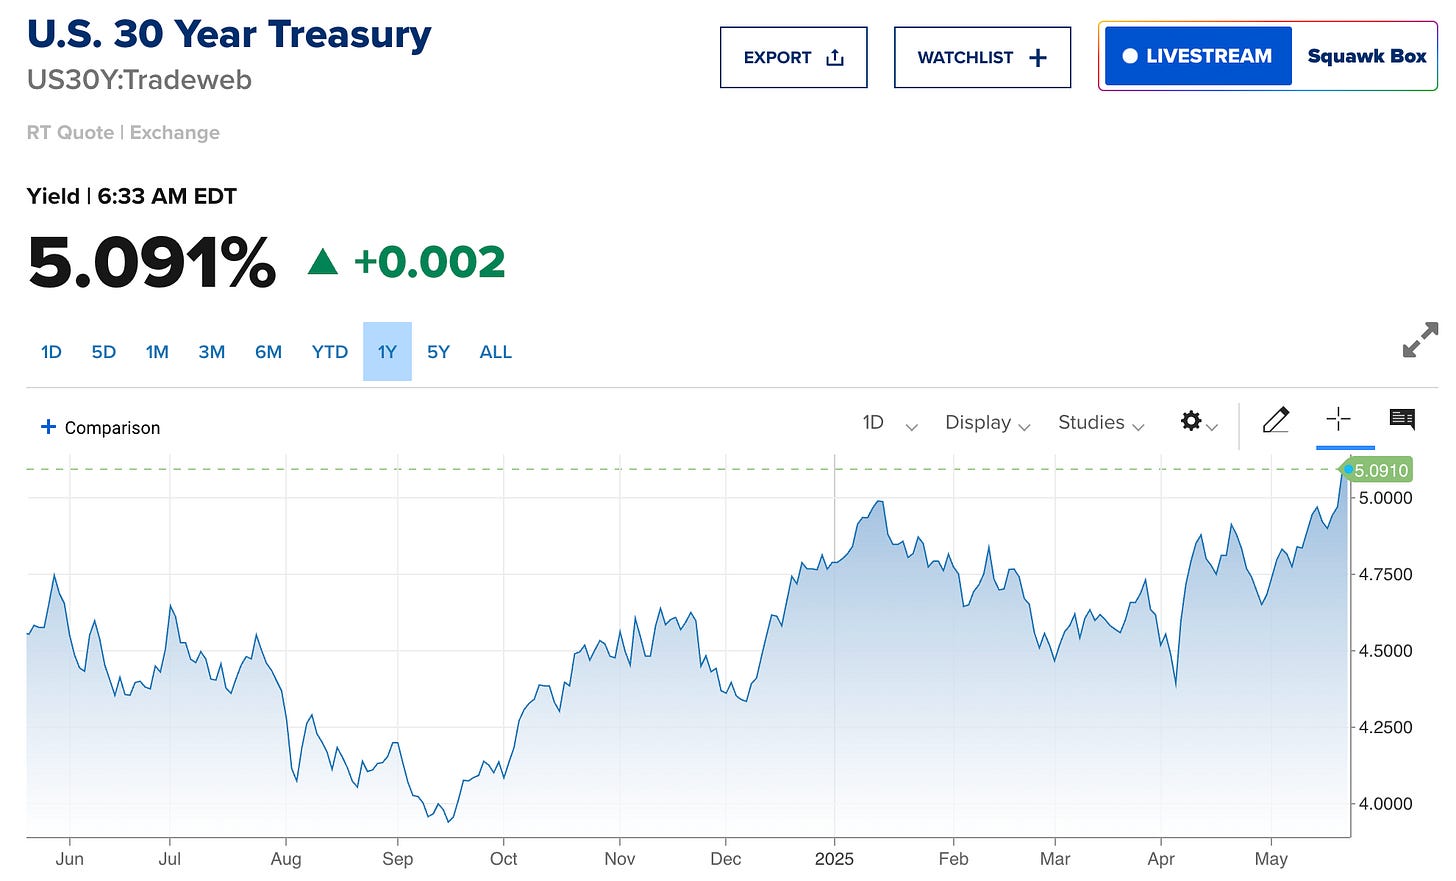
Losing any significant part of that money would force interest rates higher. You have to think that fears of a sudden stop are helping to drive up long-term rates, which keep hitting new highs:
And what would be hit if interest rates surge? The answer, overwhelmingly, is housing. A sudden stop in capital inflows would mean a severe housing crash.
Would all of this add up to a recession? Housing crashes always do, in practice, cause recessions.
Some economists might argue that this time would be different, that there would be an offsetting effect from a weaker dollar, which would eventually boost exports. The crucial word here, however, is “eventually.” Historically it has often taken a couple of years or more for a weaker dollar to boost exports, because it takes time to stand up new production capacity and open new markets — especially when the Trump trade war is closing markets around the world. Meanwhile, as anyone who remembers the last financial crisis knows, housing can crash very fast.
And let’s not forget that a plunging dollar would drive up inflation, probably forcing the Federal Reserve to raise interest rates rather than cutting them despite a recession and rising unemployment.
So a sudden stop would be a very ugly experience for America — a recipe for lots of economic pain and a bout of stagflation. And recovery would be difficult. The Fed’s hands would be tied by stagflation. And to recover the world’s confidence, American policymakers wouldn’t just have to become far more responsible than they are, but they’d have to convince the world that they’d changed, a very tall order.
Now, we don’t know that we will indeed face a sudden stop. America has never had one in the past. But the danger is real, because the rest of the world is figuring out with each passing day that we aren’t the country we used to be.
Whatever
Tags
Who is online
84 visitors
But hey! Who gives a fuck?
Obviously not democrats who fight every attempt to simply cut the rate of spending growth like it’s the apocalypse.
If we need to cut spending, why are we re-upping a tax plan that gives almost all of the benefit to the rich? The "big beautiful bill" is adding trillions to the national debt, and that is even with all the social spending cuts.
One day people will realize that an unequal economic system like capitalism has to have leavening factors like taxes , and heavy taxing of the rich. It is the only way that will ever work, unless you want a revolution.
"Conversations" with MAGA_True_Believers© here on NT have become a total waste of time. MAGA_True_Believers© almost never propose anything; they deny, deflect, derail. They waste everyone's time. I, for one, have decided not to let them waste any more of my time. From now on, I will simply copy/paste this in response to "standard" MAGA_True_Believer© Comments.
Be well.
"Conversations" with MAGA_True_Believers© here on NT have become a total waste of time. MAGA_True_Believers© almost never propose anything; they deny, deflect, derail. They waste everyone's time. I, for one, have decided not to let them waste any more of my time. From now on, I will simply copy/paste this in response to "standard" MAGA_True_Believer© Comments.
Be well.
Don't I recall you giving a fck when Trumps Independence had consequences ?
What exactly are you talking about?
I apologize if I've mistaken you for another, but were it not you who byTrumps proposed on again, off again, on again, off again, off again, on again, off again, off again, till on again tarriff definitive and oh so definitely exactlly as he has described them in so many fabulous facets, that it tyrned on a spicket, that took monies, some in amounts wicked, witch I thought you had expressed displeasure with the Em per ore, cause I thought U had stated part of the worlds economy, in the trillions, did evaporate directly via Trump indecision about instilling, then unstilling, till unsettled enough to insettlemeant for the non quite so much as US gang of peep holes who peer to not a pier too closely, as what Trump appears to make dissapear beside a super Tanker filled with Diamonds of the Sea Cucumbers cumbersome to sum, sum , not so much unless added to the gratuity tip that Trump did trip over when arranging his twisted sister and brother game of Tarriff/Market manipulations in where as he, his Buds on Wall Street, and select others were instructed on how to prosper in the absolute positive with the info wtae are about to provide/ sorta like Inside/ trade for outside the box thinking about monetary mythical little tiny bitties of coins, as magic money sure do behave funny , especially when directed to do just that, and that it did and I thought you werre unhappy with Trump crappy costing your retirement nest egg a bit, my bad if i have you confused, with me, cause i'm confused, or are I am confused about the confusiocaused when no conclusion as to the now know inspirational delusion that mass confusion couldcause if it had not, quite the confusion. Trump is a Con man fused to be shunned, thus
Trump = Confusion = Trump
wait a minutre,
i think im a little confused....
but, 'm not sure how i wound up this way, around the way that used to play this way while weighing way less than the weight prior to previous visits pertaining to prior prioriteasses my heir apparent that calls, calls for me to get and stay busy, in the call waiting waiting room where one learns to be a waitress looking for a Mate Drrr D, to serve as her waiter even though impatiently impatient when the in-patient is and has, patience run out of the hospital due to impatient patience using up theirs, as impatiently waiting , tables at call waiting waiting room for waitresses looking for their sole Mate Drrr D, fending of Oh phenders with bumpers on Cars driven too fars
This stopped being a post to you somewhere round the beginning, then smokey smokey and off and wokey up thinking differently than say most do every single same morning that the same differences are differences, thus being the same....its the weed, have to blame something, accept that which i'll own, cause i didn't right it, yet, id right it like im a full of ship lapped siding solicitors needing Tin Man Oil Cans of bottled soup till nuts, on them the soup spilled, like beans, when baked, when heads, are faked
[✘]
[✘]