
Stock market highs in today's AI boom mirror the dot-com bubble


 S E E D E D C O N T E N T
Oct. 15, 2025, 8:05 AM EDTBy Christine Romans
It seems nothing can hold back the bulls on Wall Street — not trade wars or interest rates or nagging concerns over the cost of living.
Fueled by trillions in spending on artificial intelligence, U.S. stock markets are setting record highs. In the past three years, the tech-heavy Nasdaq Composite Index has doubled.
Federal Reserve Chairman Jerome Powell recently called stocks "fairly highly valued."
If all this frothy optimism has you humming Prince and partying like it's 1999, you're not alone.
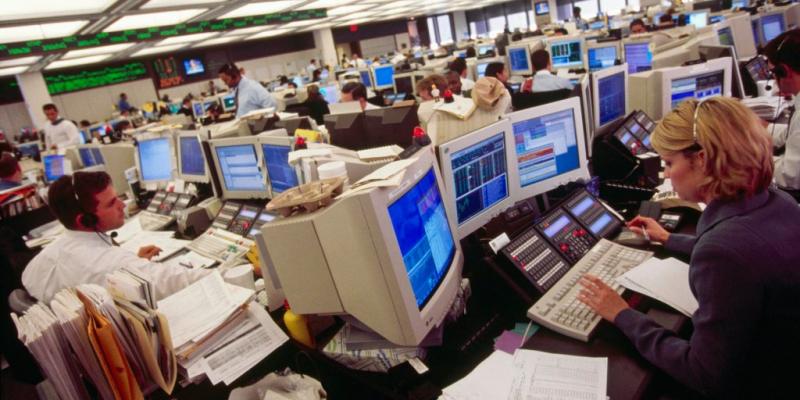
Twenty-five years after the first internet bubble burst in March 2000, investors and analysts are starting to draw comparisons between today's AI boom and the dot-com bubble of the late 1990s, which ended with a crash.
Some investors say AI isn't helping enough companies make money and therefore isn't actually growing the economy.
Others say the massive investment deals recently announced among a small group of AI giants are effectively "circular" because money and stock pass back and forth between parties in such transactions.
Billionaire hedge fund investor Paul Tudor Jones said this "Bubble 2.0" could be even bigger than the last one.
"If anything, now is so much more potentially explosive than 1999," Tudor Jones, the founder and chief information officer of Tudor Investment Corp., said this month on CNBC's "Squawk Box."
Back then, the internet was new and transformative. And just like today, companies that didn't yet turn a profit were some of the darlings of Wall Street.
But there was skepticism, too.
Legendary investor Warren Buffett — known as the Oracle of Omaha — likes to look at the ratio of total stock market valuation relative to the size of the U.S. economy, or gross domestic product.
His measure, known on Wall Street as the "Buffett Indicator," reached a record high over 140% during the dot-com boom, right before the market crashed.
Today, the Buffett Indicator is above 210%, dwarfing its peak 25 years ago.
"If the ratio approaches 200% — as it did in 1999 and a part of 2000 — you are playing with fire," Buffett, the chairman and CEO of Berkshire Hathaway, wrote in Fortune magazine in 2001.
For now, markets are on fire — a lot like they were in the go-go days of the late 1990s.
In 1996, then-Fed Chair Alan Greenspan warned of an "irrational exuberance" that had taken hold of investors and might have "unduly escalated asset values."
He would eventually be proven right, but not for three more years. And during that time, the Nasdaq more than doubled before the bubble finally burst.
Today, top tech analyst Dan Ives thinks there's still room to run.
"This AI arms race, we're in a 1996 moment today, not a 1999 moment," Ives, a managing director at Wedbush Securities, said on CNBC's "Closing Bell" this month.
But others are more cautious.
JP Morgan Chase CEO Jamie Dimon told the BBC on Thursday that he's concerned about a broader stock market "correction" — when a stock index loses more than 10% of its value.
"I am far more worried about that than others" in the financial industry, he said.
Nonetheless, "I'm not saying next year," Dimon added. "Because the timing of these things is almost impossible."
Even for the smartest people in the industry, calling a bubble is one thing, but timing it is another.

Tags
Who is online
119 visitors
I'm not sure the current AI investments bear much similarity with the dot com bubble. The dot com bubble was based on potential (just as AI investments today) but the dot coms did not have a clear path to profitability and were entirely dependent upon public adoption (eyeballs). Much of the investment in dot coms involved expansion of infrastructure (like fiber optic networks) in anticipation of increasing demand that didn't really pay off.
There isn't uncertainty about how AI can become profitable in a B2B environment. Public adoption is less critical to AI profitability. And demand for AI application is outpacing ability to supply that demand. On top of that, the rapid pace of developments in AI supports speculation for increasing future valuation.
The current investment frenzy over AI has much less uncertainty and has provided more tangible results than did the dot com bubble. If AI development stalls at the current pace of investment then a bubble could grow rapidly and become a real risk. But that doesn't seem to be the case now.