
Biden's Proposal to Empower I.R.S. Rattles Banks and Their Customers

By: Kate Kelly and Alan Rappeport (MSN)

 S E E D E D C O N T E N T
When the Biden administration looked for ways to pay for the president's expansive social policy bill, it proposed raising revenue by cracking down on $7 trillion in unpaid taxes, mostly from wealthy Americans and businesses.
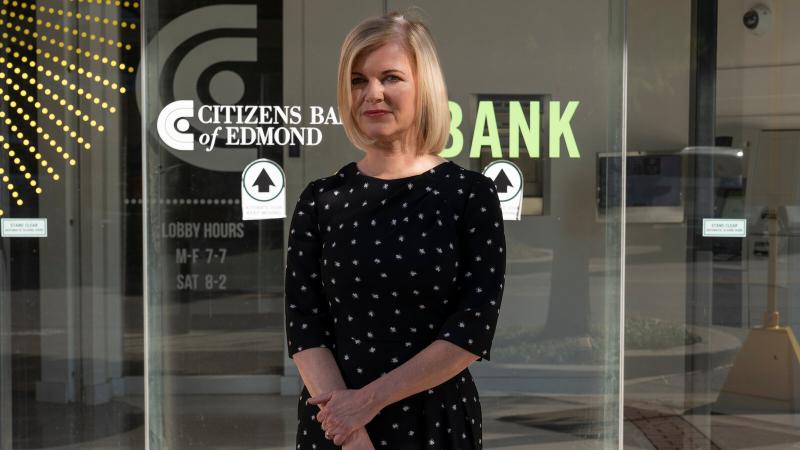
© Nick Oxford for The New York Times "We have heard a lot from our customers about their concerns about their privacy," said Jill Castilla, the chief executive of the one-branch Citizens Bank of Edmond, just outside Oklahoma City.
To help find those funds, the administration wants banks to give the Internal Revenue Service new details on their customers and provide data for accounts with total annual deposits or withdrawals worth more than $600. That has sparked an uproar among banks and Republican lawmakers, who say giving the I.R.S. such power would be an enormous breach of privacy and government overreach.
Banks and their trade groups are running advertising and letter-writing campaigns to raise awareness — and concern — about the proposal. As a result, banks from Denver to Philadelphia say they are being deluged with calls, emails and in-person complaints from both savers and small-business owners worried about the proposal. JPMorgan Chase & Company has issued talking points to bank tellers on what to tell angry customers who call or come into a branch to complain.
© Stefani Reynolds for The New York Times The Internal Revenue Service in Washington. The I.R.S. would receive data for bank accounts with total annual deposits or withdrawals worth more than $600 under the proposal.
Sign up for The Morning newsletter from The New York Times
Load Error
"We have heard a lot from our customers about their concerns about their privacy," said Jill Castilla, the chief executive of the one-branch Citizens Bank of Edmond, just outside Oklahoma City. "I've gotten calls, emails, and then we've had many customers come in."
Banks already submit tax forms to the I.R.S. about the interest that customer accounts accrue. But the new proposal would require they share information about account balances so that the I.R.S. can see if there are large discrepancies between the income people and businesses report and what they have in the bank. The I.R.S. could audit or investigate the gaps to see if those taxpayers are evading their obligations.
Biden administration officials say the United States needs more information from taxpayers to crack down on those who do not pay what they owe. The measure, which would affect more than 100 million households and millions of businesses, is estimated to capture $460 billion in additional revenue over a decade, primarily from the wealthiest Americans.
"This is a very serious policy proposal," Treasury Secretary Janet L. Yellen said at a congressional hearing last month. "We have a $7 trillion estimated tax gap that we have a great deal of tax avoidance by individuals and businesses — typically very high-net worth, high-income individuals and businesses that have opaque sources of income that are not paying the taxes that are due."
Treasury officials say the effort is not about tracking individual transactions and is not aimed at lower- or middle-class households. The $600 threshold was chosen to weed out accounts that are generally dormant or get little use, such as children's accounts, while still giving the government the broadest possible visibility. Administration officials say audit rates for taxpayers who earn less than $400,000 per year will not go up.
"This is about making sure the top 1 percent can't evade $160 billion per year in taxes," said Alexandra LaManna, a Treasury Department spokeswoman.
Top Democrats say that empowering the I.R.S. is key to making the economy more fair. Senator Elizabeth Warren of Massachusetts has warned that the I.R.S. is handicapped when it comes to tracking the income of the wealthiest.
"The kinds of income that the I.R.S. has the least visibility into are the kinds of income that are overwhelmingly concentrated among the very richest taxpayers," Ms. Warren said. "Strengthening information reporting, as well as providing protected and sustained I.R.S. funding, would ensure that we focus enforcement on the biggest fish."
But the pushback is putting pressure on the Biden administration to scale back the proposal. Lawmakers are discussing raising the required disclosure level to $10,000 rather than $600, a Treasury official said, and making taxpayers who are paid through payroll-processing companies exempt from the required reporting. The Treasury estimates that could reduce the amount of money it could recoup to between $200 billion and $250 billion over a decade.
The outcry over the proposed measures stems in large part from a carefully planned lobbying campaign by the banking industry, which has spent months raising awareness and opposition to the plan in cities and towns across the country.
Banks say the reporting requirements would raise their costs and put them in the unenviable position of handing customer information over to the I.R.S.
Top industry trade groups have hammered the proposal in emails and phone calls to members. They have argued their case in meetings with senior administration officials, including Ms. Yellen and Charles P. Rettig, who runs the I.R.S. They established a social media hashtag, #KeepMyBankingPrivate, that some executives have used in sharing their doubts about the proposal.
"We proudly join @ICBA and others in telling Congress that we serve our customers, not the IRS," Bankcda, whose main branch is in Coeur d'Alene, Idaho, wrote in a recent Twitter post tagging the Independent Community Bankers of America, a trade group that caters to smaller banks and is helping to lead opposition to the measure.
After the initiative made its first appearance deep in the Treasury's annual budget proposal in May, the American Bankers Association said it and its state-level partner groups quickly heard from hundreds of member banks, raising questions about the idea and its implications. The Independent Community Bankers of America began flagging the potential changes to its members, prompting many of them in turn to alert their customers.
Trade groups also helped gather signatures for a Sept. 17 letter to congressional leaders complaining about the proposal.
"Indiscriminate, blanket data collection would amount to a troubling effort to profile American taxpayers based on account characteristics without grounds for suspicion of tax evasion," the letter argued. It was signed by more than 40 business groups, including the Mortgage Bankers Association, Global Cold Chain Alliance and Foodservice Equipment Distributors Association.
Awareness of the proposal has been amplified by ad campaigns, conservative news media coverage and Facebook posts, including one that caught the attention of Crystal Causey, a 39-year-old advertising account executive in Los Angeles.
"I wouldn't allow my husband or my parents to monitor my bank account activity," she said in an email. "There's no way I would be OK with the government monitoring it."
Industry representatives say it is unusual to see banks communicate with their account holders on a political matter. "This is the first time in 20 years that I've seen that banks have reached out to inform their customers on an issue" like this, said Paul Merski, who runs congressional relations for the community bankers association.
Jim Reuter, the chief executive of FirstBank near Denver, said concerns about the potential provisions have bubbled up frequently, including over a coffee he had with a small-business owner in early October.
"Their upshot is, 'I pay my taxes, so why would you be sending additional information to the I.R.S.?'" Mr. Reuter recalled. "I said I agree with them. We're in the trust business. And it just goes without saying that sending the customer's information somewhere without giving consent — that's not what we do as a bank."
The proposal's critics have said the I.R.S. appears ill-equipped to process and safeguard such an overwhelming amount of data to actually catch cheats.
"I have to tell you the proposal that has been put forth about expanding the amount of information that the I.R.S. is going to get on private bank accounts has been something I've been asked about at parks, at grocery stores, at convenience stores around the district," Representative Trey Hollingsworth, Republican of Indiana, told Ms. Yellen at the congressional hearing last month. "This has people deeply afraid about the emergence of an apparatus that can be used against them."
J.P. Freire, a spokesman for Representative Kevin Brady of Texas, the top Republican on the House Ways and Means Committee, said Texans were "terrified" of the I.R.S. and that his boss was fielding inquiries about the proposed disclosures from at least three or four constituents every week.
Ms. Castilla, the community banker in Oklahoma, said a local schoolteacher had stopped by her office two weeks ago to share her anxieties about the idea of the government peering into her financial records. She told the teacher she believed the proposal was an overreach, Ms. Castilla recalled, and added that banking associations and Oklahoma's congressional delegation were fighting it.
Even if the dollar threshold were raised to $10,000, Ms. Castilla said, it would still be onerous for her bank. "This would require a massive amount of infrastructure," she said.
Treasury officials say they are flummoxed by the outrage, given that banks of all sizes initially told them they could comply with the rules, which would not take effect until 2024.
"They have made clear during conversations with banks that firms can easily implement a simple proposal like the one under consideration in Congress, and that any compliance costs would be minimal," said Ms. LaManna, the Treasury spokeswoman.
Continue ReadingShow full articles without "Continue Reading" button for {0} hours. Microsoft and partners may be compensated if you purchase something through recommended links in this article.

Tags
Who is online
107 visitors
Yea or nay??
If they know there's $7T unpaid, why haven't they gone after the deadbeats prior to now???? Isn't that why there IS an IRS?
They are underfunded and have been for decades. While this thing sounds ominous, they still won't have the resources to do an adequate job will target low hanging fruit to make it look like they are actually doing something.
I don't quite understand if the purpose is to go after the wealthy and businesses, why is the limit for reporting set at $600? Seems rather low to me.
And I have to agree with the thrust of the article, this is about privacy rights also. If I have not broken any tax laws and there is no belief that I have broken any tax laws why would they need to look at my banking transactions. It's like searching for a crime rather than having the suspicion that a crime has been committed and getting a search warrant.
I see this as nothing more than the opportunity to grow government (again) and to gain more power over the people. The wealthy and large businesses will do what they have always done is move their money to 'friendlier' locations. This will then create another large burden on business (banking) which will cost more money which will further inhibit the economy.
They are looking for people who are skirting tax laws, by getting paid via cash, bitcoin or smart phone apps. For the record, I don't like it anymore than you do.
Y'think?
This is cracking down mostly on wealthy Americans and businesses yet the IRS cares about annual deposits/withdrawals of more then $600 per year. Someone banking at a rate of more that $600 per year is on the radar? How about banking at a rate of more than $600,000 per year?
The IRS already looks at transactions $10K or more under terrorism laws.
They don't need to reduce it to $5k. $7trillion in tax avoidance doesn't happen in $5k increments.
Tax avoidance is not tax evasion
Regardless, people with $10million are not doing either in increments of $5k.
$460 billion over a decade from the wealthiest and this involves almost 100 million households. Households?? The USA has about 122 million households in total. How does going after 100 / 122 or 82% of US households translate into 'the wealthest'?
$460 billion over a decade??
This does not compute.
You're right, it really does not compute.
And from Reuters...
So they estimate they will collect an average of $46 billion a year. But they also estimate they lose $1 trillion a year. So that's a HUGE net loss...
And how much is this added reporting requirements going to cost both the direct consumer (banks & banking customers) as well as act as a drain on the economy? When you take money out for the execution of such a program, it is not money that is then going into the economy after all.
Yes, ~100 million households would be affected.
All sorts of small-scale evasion routinely takes place. Most of the small construction contractors routinely use cash to help avoid paying taxes. IMO if they did not do so, they would go out of business due to low margins. Also, how many housekeepers, etc. work on a cash basis?
Going after these people, who largely are paycheck-to-paycheck is, IMO, misguided. If the government wants to crack down on income tax evasion (as well as legal but excessive avoidance) then they should do what they advertise and focus on the 1%. If the 'wealthy' are to pay their 'fair share' then why go after Joe 6-Pack's local remodeling business?
The unintended but utterly foreseeable consequence of this will be to push these people away from banks. The "unbanked" are traditionally the most economically vulnerable of American society, so by all means we should add to their ranks as aggressively as possible.
Once again late to the party and off topic as usual.
I take it you are OK with the Democrats plan that will use the IRS to target low and middle income tax payers? Despite their forked tongued assurances.
Technocrats always think more data is the answer. It's a way for smart stupid people to kick the can.
An expectation that this proposal will increase revenue by $460 billion over a decade ($46 billion per year) won't do anything to address trillion dollar deficits. And the added cost to collect and process the data will eat up most of the revenue that's obtained. It's highly unlikely the wealthy are using commercial banking to avoid taxes anyway. Yellin's proposal is to spend a dollar of someone else's money to get a nickel.
There are two problems. The first is a tax code so contorted and perverted that no one (including the IRS) really knows how much taxes are owed. The wealthy are using the tax code to avoid taxes; tax avoidance is built into the tax code. The second is a government that spends money without regard for revenue. Technocrats collecting more data won't address either of those problems.
Reinstating Glass-Steagall would do more than Yellin's proposal. Fiduciary requirements would do more than Yellin's proposal. But financial technocrats don't want to do anything that would regulate Wall Street. These financial wizards will kill the working class before interfering with the ability of the wealthy to cheat. In finance, cheaters always win. Cheating is the business model for investment banking and finance.
Given the IRS's long history of abusing it's power, how could anyone possibly think this is a good idea?
Another take on the issue:
Republicans Mischaracterize Proposed Financial Reporting Requirement
Also:
Fact check: Claim about the IRS monitoring bank accounts over $600 exaggerates reality
To use the local terminology, that's a shit ton of "gaming the system" for a person trying to hide their side hustle that grosses 10k annually. Granted, there may be taxes to pay on a $10,000 a year side hustle, and I'm not condoning hiding it. There is a difference in needing a 1099 for $600 or more earned from a prize, non-employer, etc., and flagging accounts that see $600+ in activity over a given year though.
As to the factcheck sites...
1st, proposals turn into rules. 2nd...Great, so the IRS won't know where the money was spent, or where it came from...until it audits your ass. Here's the scenario again. I have a garage sale, I deposit the proceeds of the sale into my regular account, because I'm not one of these nefarious bastards that has over 21 accounts to hide $12,000.00. The only monies in and out of my account are my wages (which are already reported) and my garage sale proceeds. Now, the IRS is auditing my ass, nevermind the fact that I took a loss at the garage sale, because my account ledger doesn't match my pay stubs. Let's not forget the IRS is now spending thousands on agents to sift through my shit, when it will not net any return. If they want to waste money, paying for someone to look for something, they can pay me $65k a year to search my property for gold. I'll turn every bit I find over to the feds.